Cash Offer Calculator for Home Value Estimation with Instant Quotes
This guide is going to walk you through how cash offer calculators actually work, what they get right, what they miss, and — most importantly — how to use that information as a starting point rather than an ending point when you're navigating one of the hardest transitions your family will ever face.
Key Takeaways
- Cash offer calculators give you a ballpark estimate based on public data — they are a starting point, not a final number, and they don't account for your home's specific condition or local market nuances.
- The difference between an automated estimate and a real cash offer can range from 5% to 20% depending on the home's condition, location within the DFW market, and how quickly you need to close.
- Families selling a parent's home to fund assisted living or memory care have unique timing pressures — the right sale process accounts for those deadlines, not just the price.
- A fair cash offer isn't just about the number — it's about transparency, no hidden fees, no repair demands, and a closing timeline that works for your family's care situation.
- You don't have to choose between fast and fair. With the right buyer and the right conversation, you can have both — and still feel good about how it was handled.
- Understanding what goes into a home value estimate gives you real negotiating power and protects you from rushed decisions made under emotional pressure.
What a Cash Offer Calculator Actually Does (And What It Can't)
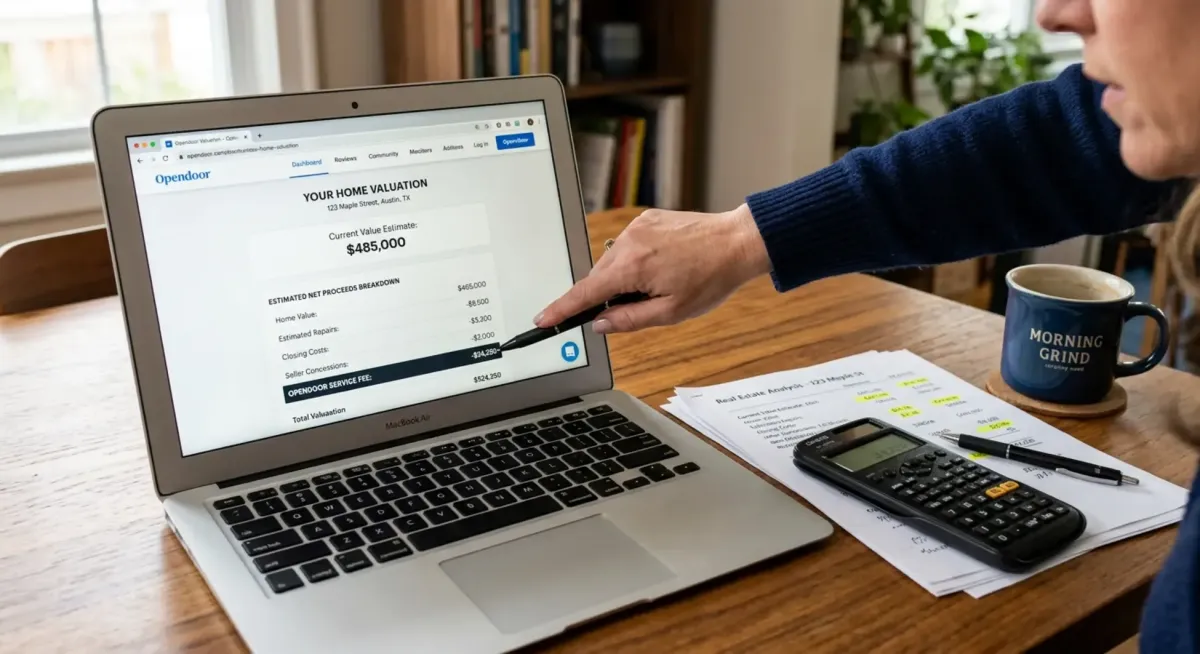
Let's start with the mechanics, because understanding how these tools work is the first step to using them wisely. When you type an address into a cash offer calculator — whether it's on Zillow, Opendoor, or a local investor's website — you're essentially asking an algorithm to pull together publicly available data and spit out a number.
That data typically includes recent sales of comparable homes in the same zip code, the home's square footage and lot size from tax records, the year the home was built, the number of bedrooms and bathrooms on record, and sometimes basic neighborhood trend data like whether values have been rising or falling over the past 90 days.
What it cannot see — and this is where families get into trouble — is everything that makes your parent's specific home different from the averages. The calculator doesn't know that the roof is 22 years old. It doesn't know the HVAC system hasn't been serviced since 2015. It doesn't know the kitchen still has the original 1978 linoleum, or that there's a foundation crack in the garage that's been there for years. It doesn't know that the backyard backs up to a busy road, or that the master bathroom was updated beautifully just three years ago.
All of those factors — the ones that actually determine what a buyer will pay — are invisible to an automated calculator. This is why you'll often see a disclaimer in small print that says something like "estimate accuracy: ±15%." On a $300,000 home, that's a $45,000 swing in either direction. That's not a rounding error. That's a significant portion of a year's worth of memory care.
See What a Fair Cash Offer Might Look Like for Your Parent's Home
Our cash offer calculator gives you a transparent, real-world estimate based on how buyers in the DFW market actually evaluate homes — not just public record data. Use it to build your baseline before any conversation with a buyer.
What "Instant Quote" Really Means: When a website offers you an "instant cash offer," they're typically showing you an automated valuation model (AVM) estimate — not a real offer from a real buyer. A genuine cash offer requires someone to actually review the property, understand its condition, and commit real money. The "instant" number is a conversation starter, not a contract.
The DFW market adds another layer of complexity. Dallas-Fort Worth is one of the most active real estate markets in the country, but it's not one uniform market — it's dozens of micro-markets layered on top of each other. A home in Garland sells differently than a home in Southlake. A house in Oak Cliff has a completely different buyer pool than one in Frisco. Automated calculators often smooth over these neighborhood-level differences, which means the estimate you get might be based on comps that don't really apply to your parent's specific street.
None of this means you shouldn't use a calculator. It means you should use it the way you'd use a weather forecast — as helpful context that tells you roughly what to expect, while understanding that the real picture will only come into focus when someone actually shows up and takes a look.
The Factors That Determine a Real Cash Offer on a Senior's Home
When a legitimate cash buyer — not an algorithm — evaluates your parent's home, they're working through a specific set of factors that directly shape the offer they make. Understanding these factors doesn't just help you evaluate whether an offer is fair. It helps you walk into the conversation prepared, which reduces the emotional vulnerability that can lead families to accept terms that don't serve them well.
The first and most significant factor is the home's current condition relative to what buyers in that price range expect. In the DFW market, buyers in most neighborhoods have options. If your parent's home needs $40,000 in updates to compete with other listings, a cash buyer will factor that into their offer — but a good buyer will show you exactly how they arrived at that number, not just present a lower figure and hope you don't ask questions.
The second factor is what's called the post-renovation value — what the home would likely sell for on the open market after a buyer invests in repairs and updates. Cash buyers who purchase homes as-is are essentially taking on the risk and cost of that renovation work, and their offer reflects that. A transparent buyer will walk you through this math openly: "Here's what we think the home will be worth after updates. Here's what we estimate those updates will cost. Here's the margin we need to make this work. And here's what that means for your offer."
If this feels like a lot to process right now, you're not wrong. Most families dealing with a parent's care transition are already running on empty — emotionally, logistically, and sometimes financially. You shouldn't have to become a real estate expert overnight. That's exactly why having someone who will walk through these numbers with you, in plain language, makes such a difference.
The third factor is your timeline. This one matters more than most families realize. If you need to close in 30 days because the assisted living deposit is due, that urgency has real value — but it also creates vulnerability if you're working with a buyer who knows you're under pressure and uses it against you. A fair buyer will acknowledge your timeline, work with it, and not use it as a reason to lower their offer below what's reasonable.
The fourth factor is what stays and what goes. Many families in this situation simply cannot deal with clearing out decades of belongings before a sale. The ability to leave furniture, personal items, and household contents behind — and have the buyer handle the cleanout — has real monetary value that should be reflected in how you evaluate competing offers. An offer that requires you to hire an estate sale company, a junk removal crew, and a cleaning service isn't actually as high as it looks on paper.
How the DFW Market Shapes What You'll Actually Receive
Dallas-Fort Worth is consistently ranked among the top real estate markets in the United States, and that's genuinely good news for families selling a parent's home here. Strong demand, population growth, and relatively low inventory in many submarkets mean that even homes in need of significant work have real value to the right buyer.
But "the DFW market is hot" is not the same as "every home will sell quickly at a great price." The market is nuanced, and where your parent's home sits within that market matters enormously. Homes in established neighborhoods in cities like Mesquite, Irving, or Grand Prairie often attract cash buyers who are specifically looking for value-add properties — which means there's genuine competition for these homes, and that competition benefits sellers. Homes in more rural parts of the metro or in neighborhoods with declining school ratings may have a smaller buyer pool, which affects both price and timeline.
Interest rates also play a role that many families don't consider. When mortgage rates are elevated, traditional buyers — the ones who need financing — become more cautious and more selective. This actually increases the relative advantage of cash buyers, because they're not subject to the same rate-driven hesitation. For families who need to sell quickly to fund care, this dynamic can work in your favor when you're working with a cash buyer who doesn't need a mortgage contingency to close.
One thing we've seen consistently in the DFW market: families who take the time to get two or three cash offers — rather than accepting the first one that comes in — almost always end up in a better position. Not because the first offer is necessarily bad, but because having context makes you a more confident decision-maker. You're not just reacting to a number; you're evaluating it. And when you're already carrying the weight of a parent's care transition, that sense of agency matters.
The DFW Neighborhood Factor: In the Dallas-Fort Worth area, the same square footage in different zip codes can carry a $50,000–$150,000 difference in value. Before you evaluate any cash offer, make sure you know which neighborhood your parent's home is being compared to — not just the city. Ask any buyer to show you the specific comparable sales they used to arrive at their number.
Trying to figure out what your parent's home might actually be worth in today's DFW market — not just what an algorithm says? Our resources page has tools and guidance specifically for families navigating this transition.
Get Senior Living & Home Sale ResourcesThe Difference Between a Lowball Offer and a Fair Cash Offer
This is probably the question we hear most often, and it's a fair one. The fear of being lowballed is real — and it's not unfounded. There are buyers in every market who make low offers, present them with urgency, and count on the family's emotional exhaustion to close the deal before anyone asks too many questions. Knowing the difference between that kind of offer and a genuinely fair one is one of the most valuable things you can walk away from this article understanding.
A lowball offer typically has a few telltale signs. The buyer is vague about how they arrived at the number. They create artificial urgency — "this offer is only good for 24 hours" — without a real reason for the deadline. They don't want to walk through the home with you or explain their reasoning. They discourage you from getting other opinions. And when you ask questions, the answers are evasive or dismissive.
A fair cash offer looks very different. The buyer walks you through their math openly: here are the comparable sales I looked at, here's my estimate of the repairs needed, here's the post-renovation value I'm working from, and here's how I landed on this number. They invite your questions. They give you time to think. They don't disappear if you say you want to talk to a family member first. And they acknowledge that this isn't just a transaction — it's a significant moment in your family's life.
One of the things we hear from families after working with us is something like what Darla said: "We didn't get the highest offer, but we trusted you because you took the time to explain everything." That's not resignation — that's wisdom. The highest number on paper isn't always the best outcome when you factor in the full picture: the certainty of closing, the timeline, the as-is condition, the contents left behind, and the peace of mind of working with someone who treated you like a person rather than a transaction.
Red Flags in a Cash Offer Situation: Be cautious if a buyer refuses to explain how they calculated their offer, pressures you to sign within 24–48 hours without a clear reason, asks you to handle repairs or cleanout before closing, or discourages you from consulting with a family member, attorney, or financial advisor. A buyer who is confident in their offer welcomes your questions — they don't avoid them.
It's also worth understanding that "fair" is relative to the full package, not just the price. If a traditional listing would net you $20,000 more but requires three months of carrying costs, $15,000 in repairs, staging, showings, and the emotional toll of keeping the house market-ready while your parent is in a care transition — the math might actually favor the cash offer. The goal isn't to maximize one number. The goal is to make the best decision for your family's whole situation.
Using a Cash Offer Calculator as a Starting Point — Not an Ending Point
Here's how we actually recommend families use online cash offer calculators: as a confidence-building first step, not a definitive answer. Before you talk to any buyer — cash or traditional — it helps to have a rough sense of what the home might be worth. That context gives you a frame of reference so you're not walking into a conversation completely blind.
Start with two or three different tools. Zillow's Zestimate, Redfin's estimate, and a local investor's calculator will often give you slightly different numbers, and that range itself is informative. If all three are clustering around $280,000–$310,000, you have a reasonable ballpark. If one says $250,000 and another says $340,000, that wide spread tells you the automated tools are struggling with this particular property — which usually means there's something unique about the home that requires a human eye to evaluate properly.
Next, adjust mentally for condition. If the home needs significant work — roof, HVAC, foundation, kitchen, bathrooms — subtract a realistic estimate of those costs from the calculator's number. You don't need a contractor's quote at this stage; you just need a rough sense of whether you're looking at $10,000 in cosmetic updates or $60,000 in structural repairs. That adjustment gives you a more realistic sense of what a cash buyer is likely to offer.
Then, use that adjusted number as your baseline when you talk to actual buyers. If someone comes in significantly below your adjusted estimate, ask them to walk you through their reasoning. If their explanation makes sense — if they've identified issues you hadn't fully accounted for — that's valuable information, not a red flag. If their explanation is vague or they can't justify the gap, that's worth paying attention to.
Step 1: Get Your Ballpark
Use 2–3 online calculators to establish a rough value range. Note the spread between estimates — a wide range signals a home that needs human evaluation.
Step 2: Adjust for Condition
Mentally subtract realistic repair costs from the calculator estimate. This gives you a more accurate picture of what a cash buyer will likely offer.
Step 3: Get Real Conversations
Talk to 2–3 actual buyers — not just algorithms. Ask each one to explain their number. Compare not just the offers but the transparency and process.
Step 4: Evaluate the Full Package
Consider timeline, as-is condition, contents left behind, and certainty of closing — not just the headline number.
Step 5: Make a Decision You Feel Good About
The right decision is the one that serves your family's care situation, financial needs, and emotional wellbeing — not just the one with the highest number.
See What a Fair Cash Offer Might Look Like for Your Parent's Home
Our cash offer calculator gives you a transparent, real-world estimate based on how buyers in the DFW market actually evaluate homes — not just public record data. Use it to build your baseline before any conversation with a buyer.
Figuring out how to pay for a parent's care while also managing the home sale is one of the hardest parts of this whole process. Our guide to paying for long-term care walks through the options families in DFW actually have.
Get the Guide to Paying for Long-Term CareWhen the Home Sale and the Care Decision Are Happening at the Same Time
This is the part that most real estate content completely ignores, and it's the part that matters most to the families we work with. Selling a parent's home is almost never just a real estate decision. It's happening alongside — and often because of — a care transition that is emotionally consuming, logistically complex, and financially urgent.
Maybe your dad had a fall and the doctor has made it clear he can't go back to living alone. Maybe your mom's memory has been declining for two years and you've finally found a memory care community that feels right, but the deposit is due in three weeks. Maybe you've been named power of attorney for a parent who can no longer manage their own affairs, and you're trying to figure out how to fund their care while also honoring what they would have wanted for their home.
In every one of these scenarios, the home sale isn't happening in a vacuum. It's happening under real time pressure, real emotional weight, and real financial stakes. And that changes what "the best outcome" actually looks like.
We've worked with families where the assisted living community needed a 60-day financial commitment before they'd hold a room. We've worked with families where the memory care deposit was $5,000 and they needed to close early to access those funds. We've worked with families where the adult child was managing the sale from out of state, dealing with their own health challenges, and simply could not handle the logistics of a traditional listing. In each of these cases, the right answer wasn't the one that maximized the sale price in isolation — it was the one that made the whole situation workable.
A Story That Stays With Us: Linda and her husband had lived in their DFW home for 30 years. She was in cancer treatment. He was losing mobility. Their house was full — decades of a life well-lived — and they were embarrassed to let anyone see it, but they needed to move quickly into a senior apartment.
Within 30 days, they sold directly, closed early to help with care costs, and moved without packing, cleaning, or making a single repair. They didn't have to stage the home or endure showings while Linda was going through treatment. They left behind what they couldn't take and let us handle the rest.
What they said afterward: "You made this so much easier than we expected. You didn't pressure us, you helped us understand." That's what this process should feel like — not a transaction, but a transition handled with care.
If you're in a situation where the care decision and the home sale are happening simultaneously, the most important thing you can do is find a buyer who understands both sides of that equation — not just the real estate side. Someone who asks "How's Mom doing?" before they ask about the house. Someone who knows what a placement agent does, who can connect you with an elder law attorney if you need one, and who understands that the proceeds from this sale aren't just money — they're the funding mechanism for your parent's safety and care.
What to Ask Before You Accept Any Cash Offer on a Parent's Home
Knowledge is your best protection in this process. Before you sign anything, there are specific questions that every family should ask — and a buyer who is operating with integrity will welcome every single one of them.
First: How did you arrive at this number? Ask them to walk you through the comparable sales they used, their estimate of repair costs, and the post-renovation value they're working from. If they can't or won't answer this question clearly, that tells you something important.
Second: What does "as-is" actually mean in your offer? Does it mean you truly don't have to make any repairs, or are there conditions buried in the contract that could require you to address certain issues before closing? Get specifics.
Third: What happens to the contents of the home? If you need to leave furniture, personal items, or household goods behind, is that accounted for in the offer? Will the buyer handle the cleanout, and if so, is there a cost to you?
Fourth: What are all the fees? A cash offer that looks strong can be eroded by closing costs, administrative fees, or other charges that weren't disclosed upfront. Ask for a complete breakdown of what you'll actually net at closing.
Fifth: What is the closing timeline, and how flexible is it? If you need to close in 30 days, can they commit to that? If you need to close early to access funds for a care deposit, is that possible? If circumstances change and you need more time, what happens?
Before You Sign: Questions to Ask Any Cash Buyer
- Can you walk me through exactly how you calculated this offer?
- What comparable sales did you use, and are they actually similar to this home?
- What specific repairs are factored into your offer?
- Does "as-is" mean truly no repairs required before closing?
- Can we leave the contents of the home — furniture, personal items — behind?
- What are all the fees, and what will we actually net at closing?
- What is the closing timeline, and how flexible is it?
- What happens if we need to close early to fund a care deposit?
- Can I have a family member, attorney, or advisor review this before I sign?
- Do you have references from other families in similar situations?
One more question that most people don't think to ask: What other options do you think we should consider? A buyer who is genuinely operating in your best interest — not just trying to close a deal — will be honest with you about whether a direct sale is actually the right path for your situation, or whether a traditional listing or another approach might serve you better. That kind of transparency is rare, but it's exactly what families in this situation deserve.
Not sure which path makes the most sense for your family's situation? A care plan assessment can help you see the full picture — the care options, the financial options, and how the home sale fits into all of it.
Get Clarity With a Care Plan AssessmentThe Multiple Paths Approach: You Have More Options Than You Think
One of the things that surprises families most when they talk to us is the realization that they have more options than they thought. The narrative around selling a parent's home often gets compressed into a binary: either you list it with a real estate agent and wait, or you sell it to a cash buyer quickly but for less. That framing is too simple, and it leaves families without the full picture they need to make a good decision.
A traditional listing with a trusted agent is absolutely a viable path for some families — particularly when there's no immediate time pressure, the home is in good condition or can be brought up to market standards without too much disruption, and the family has the bandwidth to manage showings and negotiations. In the right circumstances, a traditional listing in the DFW market can yield a strong result.
A direct cash sale makes more sense when time is a factor, the home needs significant work, the family is managing the sale from a distance or while dealing with their own health or life challenges, or the emotional cost of a prolonged listing process is simply too high. The trade-off is typically some difference in the final price — but as we've discussed, that difference is often smaller than families expect when you account for the full cost of a traditional sale.
There's also a middle path that many families don't know about: a light renovation or cosmetic update before listing. In some cases, investing $10,000–$20,000 in targeted updates — fresh paint, new flooring, updated fixtures — can meaningfully increase the sale price and attract a larger pool of buyers, while still allowing for a relatively quick sale. This path requires more upfront investment and coordination, but for homes that are fundamentally sound and just need some freshening, it can be worth exploring.
And then there are situations where the home isn't sold at all — at least not immediately. Renting the property while a parent is in care, using a reverse mortgage to fund care costs, or exploring bridge loan options are all paths that some families find useful depending on their specific financial and care situation. These aren't right for everyone, but knowing they exist is part of making an informed decision.
You Don't Have to Figure This Out Alone
The families we work with consistently tell us that the most valuable thing we did wasn't buying their home — it was helping them understand all their options before they decided anything. We have relationships with trusted placement agents who can help find the right care community, elder law attorneys who can navigate POA and estate questions, and financial professionals who specialize in senior care funding. If you're not sure where to start, that's exactly where we start too.
Frequently Asked Questions About Cash Offer Calculators and Home Value Estimates
How accurate are online cash offer calculators for homes that need repairs?
Online calculators are generally less accurate for homes in need of significant repairs because they rely on public data that doesn't reflect condition. Most automated valuation models have a stated accuracy range of ±10–15%, but for homes with deferred maintenance, outdated systems, or structural issues, the real-world gap between the estimate and an actual cash offer can be even wider — sometimes 20% or more. The calculator gives you a useful starting point, but it should always be followed up with a real conversation with an actual buyer who has seen the home in person.
How much less than market value should I expect from a cash offer?
This is one of the most common questions families ask, and the honest answer is: it depends on the home's condition, the local market, and who you're working with. A legitimate cash buyer typically offers somewhere between 70–85% of the post-renovation value — but that percentage becomes much more meaningful when you subtract the cost of repairs, carrying costs during a traditional listing, agent commissions (typically 5–6%), and closing costs. When you do that math, the net difference between a cash sale and a traditional listing is often much smaller than the headline numbers suggest. In some situations — particularly when the home needs significant work or time is a factor — a cash sale can actually net more after all costs are accounted for.
Can I sell my parent's home as-is if it's full of furniture and personal belongings?
Yes — and this is one of the most significant advantages of working with a direct cash buyer. Most cash buyers who specialize in senior transitions will purchase the home with the contents included, handling the cleanout themselves after closing. This is a genuine financial and emotional benefit that families often underestimate. Hiring an estate sale company, junk removal crew, and cleaning service can easily cost $3,000–$8,000 or more, and the emotional toll of sorting through decades of belongings is significant. When you're comparing offers, make sure you're accounting for whether the buyer requires a clean, empty home or is willing to take it as-is with contents.
How quickly can a cash sale actually close in the DFW market?
A genuine cash sale — where the buyer has funds available and isn't subject to financing contingencies — can typically close in as few as 7–14 days if all parties are ready. More commonly, families choose a 21–30 day timeline to allow time for title work, document preparation, and coordination with the care transition. The flexibility of the timeline is actually one of the key advantages of a cash sale: if you need to close early to access funds for a care deposit, that's often possible. If you need a few extra weeks to coordinate the move, that's usually accommodatable too. The key is communicating your needs upfront and working with a buyer who is genuinely flexible.
What if I'm not sure whether to sell to a cash buyer or list with a real estate agent?
The honest answer is that both paths can be right depending on your situation — and anyone who tells you one is always better than the other isn't giving you the full picture. The most useful thing you can do is get a clear understanding of what a traditional listing would realistically net (after repairs, commissions, carrying costs, and time on market) and compare that to a transparent cash offer that accounts for the home's actual condition. A buyer who is operating with integrity will help you make that comparison honestly, even if it means they don't end up buying your home. If a buyer discourages you from exploring your options, that itself is a red flag.
What should I do if I get a cash offer that seems too low?
Start by asking the buyer to walk you through their calculation — specifically, what comparable sales they used, what repair costs they estimated, and what post-renovation value they're working from. A legitimate buyer will be able to answer these questions clearly and specifically. If the explanation makes sense and accounts for real issues with the home, the offer may be fair even if it feels low. If the buyer can't or won't explain their reasoning, or if their repair estimates seem inflated without justification, it's worth getting a second opinion from another buyer. Getting two or three cash offers is always a reasonable approach, and any buyer who discourages you from doing so is not acting in your interest.
Ready to Get a Real Number — Not Just an Algorithm's Guess?
We know you're not just looking for a number on a screen — you're trying to figure out how to take care of someone you love while managing everything that comes with it. When you're ready to have a real conversation about your parent's home, we'll start by asking how they're doing, not what the house is worth. We'll walk through every option with you, explain our thinking clearly, and help you make a decision that feels right — no pressure, no rush, no surprises.
Schedule a Free Conversation With Our Team