Selling Your Parent's House in Bedford to Pay for Assisted Living: A Complete Guide for Families
Selling Your Parent's House in Bedford to Pay for Assisted Living: A Complete Guide for Families
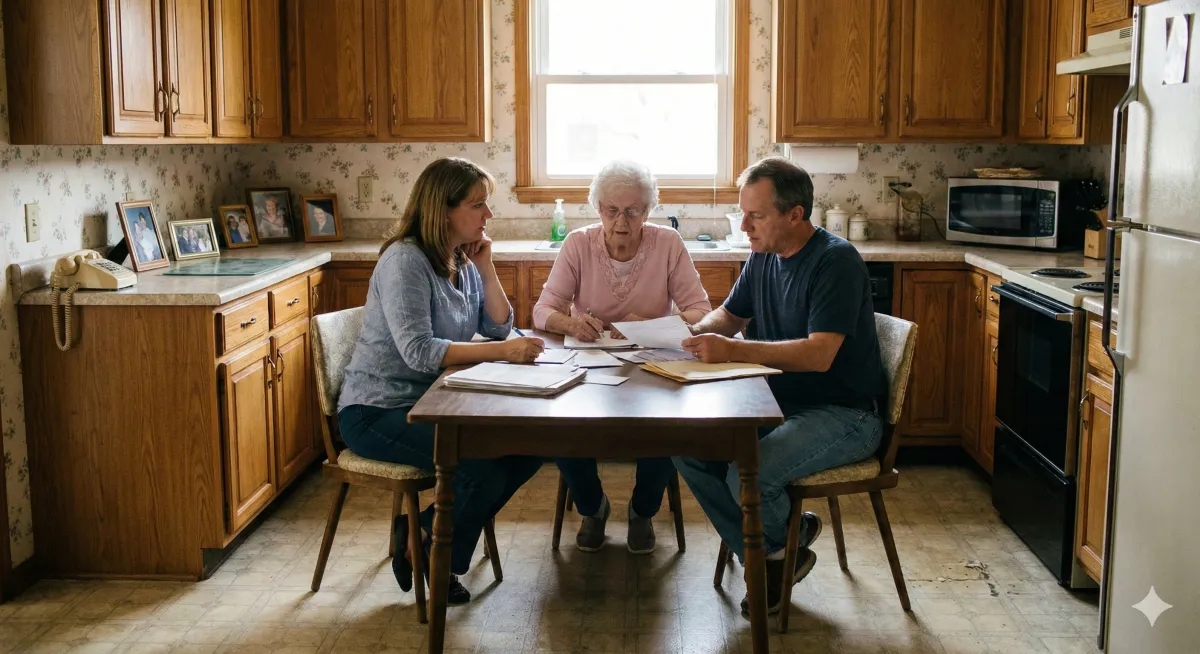
It's 2am. You're sitting in the dark, scrolling through your phone, searching "how to sell parents house for assisted living" because you can't sleep. Again.
Maybe Mom had a fall last week. Maybe the doctor just confirmed what you've been dreading—Dad's memory issues aren't just "getting older." Or maybe you've been watching your parent struggle for months, and you finally had to admit that the house they've lived in for 35 years isn't safe anymore.
Now you're supposed to figure out how to sell that house—the one with the foundation cracks you've been ignoring, the 1990s kitchen, and the garage full of decades of memories—while also finding a safe place for your parent to live. Oh, and you need to figure out how to pay for care that costs $5,000 or more per month.
If you're a Bedford family dealing with this right now, take a breath. You're not alone, and you have more options than you think.
This guide walks you through everything you need to know—from what your parent's Bedford home is actually worth today, to what assisted living really costs in Tarrant County, to selling options that most "we buy houses" companies won't tell you about.
Because here's the truth: it's not about the property. It's about getting your parent into a safe environment where they'll be cared for. The house is just how you fund that.
Key Takeaways for Bedford Families
- Bedford median home price: $380,000–$385,000. After selling costs, expect net proceeds around $350,000.
- Assisted living in Tarrant County: $3,500–$5,000/month. Memory care runs $5,000–$7,500+ per month.
- Traditional sale timeline: Approximately 65 days (35 days on market + 30 days to close).
- You have options beyond "sell fast for cheap" vs. "list with an agent and wait months."
- Tax implications vary dramatically based on whether you sell during your parent's lifetime or after—understanding this can save your family thousands.
This Is Harder Than Anyone Told You
Before we dive into the practical stuff, let's acknowledge something: this is genuinely one of the hardest things you'll ever do.
You're not just selling a house. You're closing a chapter of your family's story. You're sorting through 40 years of accumulated memories while trying to make financial decisions that will affect your parent's care for years to come. And you're probably doing all of this while working, raising your own kids, and managing your own life.
The research backs this up. Studies show that 64% of caregivers report high emotional stress, and nearly half report negative financial impacts from caregiving responsibilities. If you're feeling overwhelmed, exhausted, or like you're failing—you're experiencing exactly what millions of other adult children are going through right now.
"We're in this together—there are tools and resources to help you manage it all. And if it helps, our family made those exact mistakes too. We know what it feels like to be in your shoes."
The Panic Scenario (And Why It Costs Families Tens of Thousands)
Here's how it usually goes wrong:
Your parent falls and ends up in the hospital. While they're still in a hospital bed, the discharge planner is pressuring you to find a facility—sometimes within 48 hours. Panic sets in. You don't have $5,000 sitting around for a move-in deposit, and you certainly don't have months to wait for a traditional home sale.
So you call one of those "We Buy Houses" numbers from a postcard, accept a lowball offer, and close in two weeks. The house sells for $240,000 instead of the $320,000 you might have gotten with more time. You just lost $80,000 in equity because you were in crisis mode.
We've seen this happen to families over and over. And we've also seen families who took a strategic pause—used short-term respite care, tapped a bridge financing option, or worked with a buyer who understood their timeline—and recovered that difference.
There are ways to move quickly without sacrificing everything. That's what this guide is about.
Understanding Bedford's Real Estate Market in 2025
To make smart decisions about selling your parent's home, you need to understand what's actually happening in the Bedford market right now—not what happened three years ago, and not what some algorithm on Zillow guesses.
What Bedford Homes Are Actually Worth
As of late 2024 and into 2025, the median sale price for a single-family home in Bedford sits between $380,000 and $385,000. But that number needs context.
Bedford isn't one market—it's several micro-markets, and where your parent's home sits matters:
Zip Code 76021 (north of Highway 183, bordering Colleyville): These homes often push toward $400,000 or higher, thanks to larger lots and proximity to premium retail.
Zip Code 76022 (more mid-century ranch-style homes): Expect values closer to $350,000–$370,000.
The good news: Bedford homes are selling. The average time from listing to contract is about 34–35 days, and inventory remains tight at roughly 1.5 to 2 months of supply. In real estate terms, that's a seller's market—buyers are competing for limited homes.
The realistic timeline? If you list traditionally and everything goes smoothly, expect about 65–70 days from "For Sale" sign to cash in your account (35 days to get an offer, then 30 days to close with a financed buyer).
The Age Factor: Why Bedford Homes Need Work
Here's something that matters a lot when you're selling a senior's home: Bedford's housing stock is aging right alongside its residents.
The numbers tell the story:
36.7% of Bedford homes were built between 1980 and 1989. 20.6% were built between 1970 and 1979. That means more than half of Bedford's housing stock is now 35 to 55 years old.
If your parent bought their home in 1985 and has lived there ever since, that home is now 40 years old. Even with good maintenance, you're looking at original plumbing, aging HVAC systems, and a roof that's been through decades of Texas weather.
And if your parent is like most seniors—especially those dealing with health issues—maintenance probably slipped over the past several years. Deferred maintenance plus 1990s décor equals a home that needs significant work before it appeals to today's buyers.
Bedford Neighborhood Quick Reference
| Neighborhood | Typical Era | Market Profile |
|---|---|---|
| Harwood Oaks | Late 1980s–1990s | Premium area, lower repair risk, high demand from move-up buyers |
| Bedford Estates | 1960s–1970s | "Value play" for buyers; higher risk of foundation and plumbing issues |
| Forest Ridge | 1970s–1980s | Family favorite with scenic topography; solid resale if updated |
| Bedford Meadows | 1980s | Core "workforce" housing; high volume, strong liquidity |
| Shady Brook | 1970s | Often needs significant updating; popular with investors |
The Four Issues That Kill Deals (And Cost Families Thousands)
When you're selling a senior's home in Bedford, four major issues come up again and again during inspections. Understanding these before you list—or before you accept an offer—can save you from a deal falling apart at the worst possible moment.
1. Foundation Problems (The Big One)
Bedford sits on Eagle Ford and Woodbine geological formations, which means highly expansive clay soil. During wet springs, this soil swells. During hot, dry summers, it shrinks. This constant expansion and contraction puts tremendous pressure on concrete slab foundations.
Seniors who've lived in a home for decades often stop noticing the warning signs: hairline cracks in drywall, doors that stick, crumbling brick mortar. But home inspectors see these as red flags.
Repair costs:
Minor work (mudjacking or polyurethane injection): $3,000–$7,000
Major repair (steel or concrete pier installation): $15,000–$30,000
The critical issue: An unrepaired foundation problem often disqualifies the home from FHA or VA financing. That eliminates a huge portion of the buyer pool and often forces families to sell to cash investors at a 30–40% discount.
2. Cast Iron Plumbing Crisis
Homes built before the mid-1980s in Bedford typically have cast iron sewer pipes. The problem? Cast iron has a functional lifespan of about 40–50 years. Many Bedford homes are now experiencing "bottom channel rot," where the bottom of the pipe corrodes away and sewage leaks into the soil under the foundation.
This doesn't just create sanitary issues—it introduces moisture into the clay soil, which makes foundation problems worse.
Repair costs: A comprehensive reroute (tunneling under the slab to replace cast iron with PVC) frequently exceeds $20,000–$30,000.
3. Roofing Vulnerabilities
Tarrant County sits in a high-frequency hail corridor. Even if a roof isn't actively leaking, a buyer's insurance company may deem it uninsurable if there's visible hail damage.
Many seniors carry high-deductible policies or haven't filed claims in years. That aging roof might look "okay" to them, but it can derail a sale.
Repair costs: Full roof replacement for a typical 2,500 sq. ft. Bedford home: $12,000–$20,000.
4. HVAC System Obsolescence
Texas summers demand robust cooling systems. Units older than 12–15 years are considered at end-of-life, and older systems using R-22 refrigerant (phased out due to environmental regulations) can't be economically repaired.
Repair costs: Complete system replacement (condenser and furnace): $8,000–$12,000 per unit.
The Real Renovation Math
Here's what most families don't realize until they're deep into the selling process:
For a typical senior-owned Bedford home with deferred maintenance and 1990s décor, expect renovation costs of $60,000 minimum. When major systems also need attention (roof, HVAC, water heater, plumbing, electrical, foundation), that number can easily reach $100,000 or more.
This isn't meant to scare you—it's meant to help you understand why "as-is" selling options exist, and why the gap between a cash offer and a traditional sale might be smaller than you think once you factor in these realities.
"If you're looking at these numbers and feeling overwhelmed, you're not alone. Most families we work with are in the exact same position—staring at a home that needs work they can't afford to do, while also needing cash for care deposits yesterday."
What Senior Care Actually Costs in Tarrant County
Once you understand what you'll net from the home sale, the next question is: how far will that money go?
Assisted Living Costs
Assisted living provides housing, meals, medication management, and help with daily activities like bathing and dressing—but not 24-hour skilled nursing care.
Monthly cost in the Mid-Cities area: $3,500–$5,000
Most communities use a "base rent + care level" pricing model:
Base rent (around $3,500/month): Covers the apartment, utilities, meals, and housekeeping.
Care level add-on ($300–$1,500/month): Based on how much assistance your parent needs. A nurse assesses their needs and assigns a "level."
Budget for annual increases of 3–5%. That $4,500/month bill today will be $4,725 next year.
Memory Care Costs
Memory care provides a secured, locked environment with specialized staff for residents with Alzheimer's disease or other forms of dementia.
Monthly cost: $5,000–$7,500+
Expect a 20–30% premium over standard assisted living. This covers specialized training, security systems, and higher staff-to-resident ratios.
Move-In Costs
Community fee: $2,000–$4,000 (one-time, non-refundable)
Pet deposit: $500+ if applicable
This is often the immediate cash crunch families face—needing $5,000+ to secure a spot while the home sale is still weeks or months away.
How Long Will the Money Last?
Average assisted living stay: 22–24 months
Average memory care stay: approximately 3 years
Let's do the math on a Bedford home sale:
Net proceeds from home sale: ~$350,000
Divided by $5,000/month assisted living: approximately 70 months (nearly 6 years)
That sounds comfortable—until you factor in care level increases as needs intensify, annual rate increases of 3–5%, and the possibility of needing to transition to more expensive memory care.
A more realistic planning window: 4–5 years of coverage from home sale proceeds.
Senior Living Options Near Bedford
| Community | Care Types | Est. Monthly Cost | Notes |
|---|---|---|---|
| Heartis Mid-Cities (Bedford) | AL, MC, IL | AL: $4,950+ / MC: $5,890+ | Modern, resort-style; high engagement programming |
| Brookdale Oak Hollow (Bedford) | Memory Care only | $6,875+ | Clare Bridge dementia program specialist |
| Parkwood Healthcare (Bedford) | IL, AL, Skilled Nursing | AL: $3,400+ | CCRC model—can transition care levels on-site |
| Brookdale Eden Estates (Bedford) | IL, AL | $2,470–$3,200 | Lower entry price point |
The Medicare Myth and Medicaid Reality
One of the most common misconceptions we hear: "Medicare will help pay for Mom's assisted living." Unfortunately, that's not how it works.
What Medicare Does NOT Cover
Medicare is health insurance. It covers doctors, hospitals, and medical procedures. It does not cover custodial care—which is what assisted living and memory care provide.
Medicare will cover short-term skilled nursing rehabilitation (up to 100 days) after a qualifying 3-night hospital stay. But once your parent is stable and needs ongoing residential care? Medicare is out of the picture.
Bottom line: Do not count on Medicare to fund residential senior care.
Texas Medicaid (STAR+PLUS Waiver)
For families who exhaust their private funds, Texas offers the STAR+PLUS Medicaid waiver. But qualifying is complicated.
Asset limit: Your parent must have $2,000 or less in countable assets to qualify.
The home exemption: The home is generally exempt from counting toward assets if your parent intends to return. But once you sell it, that cash becomes a countable asset.
The 5-year look-back: Texas reviews all financial transactions from the 60 months prior to application. If your parent gifted money to grandchildren, transferred assets to your name, or sold property below market value during that window, they face a "penalty period" where Medicaid won't pay for care.
Coverage limitations: Even when approved, STAR+PLUS typically covers services (nursing, attendants) but not room and board. Your parent still needs income to cover their housing costs.
Critical reality: Many premium facilities don't accept Medicaid. If your parent runs out of private-pay funds while living in a nice community, they may be forced to relocate to a Medicaid-contracted facility—causing significant disruption and emotional distress.
Before making any asset transfers or financial decisions, consult with a Texas elder law attorney. The consequences of getting this wrong can be devastating.
Your Options for Selling (And the Truth About Each)
When it comes to selling your parent's Bedford home, you have more options than the two extremes you've probably heard about. Let's walk through each one honestly.
Option 1: Traditional Sale with a Real Estate Agent
Timeline: Approximately 65 days (35 days on market + 30 days to close)
Best for: Homes in good condition, families who can wait 2+ months
The process: You hire an agent, prepare the home (cleaning, staging, repairs), list on the MLS, hold showings, negotiate with buyers, and close with a financed buyer.
The costs:
Real estate commissions: 5–6% of sale price
Title insurance (seller pays in Texas): ~0.6–0.7%
Closing/escrow fees: ~$500–800
Repairs and concessions: 1–2% (often more for older homes)
Total: 7–9% of sale price
Net proceeds example: On a $285,000 sale (move-in ready homes are selling at $360,000), expect to walk away with approximately $259,000.
The risks: Deals fall through. Inspections reveal foundation issues the buyer can't finance. The appraisal comes in low. Each setback adds weeks to your timeline while care costs accumulate.
Option 2: iBuyers (Opendoor, Offerpad)
Timeline: As fast as 14 days
Best for: Families managing sales remotely, homes in good condition
These algorithmic buyers make instant offers based on data. The convenience is real—but so are the costs.
Typical offer: 90–95% of fair market value
Service fees: ~5%
Repair deductions: Often larger than traditional buyer negotiations
Net result: Expect $20,000–$40,000 less than a traditional sale. But you get speed and certainty.
Reality check: iBuyers are picky. Homes with foundation issues, outdated systems, or significant deferred maintenance often don't qualify for their programs.
Option 3: Cash Investors ("We Buy Houses")
Timeline: 7–14 days
Best for: Distressed properties where traditional financing isn't possible
These are the companies sending postcards and putting up bandit signs. Some are legitimate; some are not.
How they calculate offers: Most use the "70% Rule"—(After Repair Value × 70%) minus repair costs.
Bedford example:
After repair value: $385,000
× 70% = $269,500
Minus $60,000 in repairs = $209,500 offer
The trade-off: You're leaving significant equity on the table. But for homes with major structural issues that can't be financed traditionally, this may be your only realistic option.
Here's what most cash buyers won't tell you: Sometimes listing with an agent IS your best option. We've walked families through the numbers and recommended the traditional route when their home was in good enough shape to attract retail buyers. It's not about what's best for us—it's about what's best for your family.
Option 4: Senior-Focused Home Buyers
This is a newer category—companies that specifically work with families navigating senior transitions. They understand the timeline pressures, offer flexible closing dates, and often provide services beyond just buying the home (connecting families with placement agents, covering move-in costs, handling cleanout).
What to look for:
Transparent explanation of how they calculate offers
Willingness to recommend a traditional sale when it's the better option
Understanding of senior care timelines and facility requirements
Local market expertise (not a national call center)
The Honest Comparison
Let's look at a realistic scenario: a typical 1985 Bedford home with deferred maintenance and 1990s décor, but no major structural failures.
| Factor | Traditional Sale | Cash Offer |
|---|---|---|
| Sale Price | $310,000 (outdated condition) | $280,000 |
| Agent Commission (6%) | -$18,600 | $0 |
| Closing Costs (2%) | -$6,200 | -$2,000 |
| Holding Costs (3 months) | -$3,000 | $0 |
| Net Proceeds | $282,200 | $278,000 |
| Timeline | 65–90 days | 14–21 days |
| Real Difference | $4,200 | |
Now factor in reality:
You need $5,000 immediately for move-in deposits. You're paying $5,000/month for care while waiting for a traditional sale to close. Three months of care costs: $15,000.
That $4,200 "savings" from the traditional sale? It's more than consumed by care costs while you wait. And you took on zero risk of the deal falling through after inspection, no contractor coordination stress, and your parent moved into appropriate care two months sooner.
This isn't to say cash offers are always the right choice. For homes in good condition where families have time and flexibility, traditional sales still make sense. But the "cash buyers are ripping you off" narrative often ignores the full picture.
The Legal Stuff: Probate, Power of Attorney, and Protecting the Asset
The legal mechanics of selling a parent's home change significantly depending on whether your parent is living (and has capacity), living but incapacitated, or has passed away.
If Your Parent Is Living and Has Capacity
This is the simplest scenario. Your parent signs the deed, the sale proceeds normally, and they receive the funds.
But if your parent is dealing with early cognitive decline, now is the time to get documents in place before the situation progresses.
If Your Parent Is Living but Incapacitated (Power of Attorney Sales)
If your parent has advanced dementia and cannot sign legal documents, you'll need to rely on a Durable Power of Attorney.
Texas requirements:
The POA must explicitly grant authority for real estate transactions. General language like "manage my affairs" may be rejected by title companies.
The POA must be recorded with the Tarrant County Clerk before closing.
If it's a "springing" POA (only effective upon incapacity), you'll need a physician's affidavit certifying your parent's incapacity.
Critical timing: If your parent hasn't executed a POA yet and is already incapacitated, you may need to pursue guardianship through the courts—a process that takes months and costs thousands in legal fees.
If Your Parent Has Passed Away
When the homeowner dies, the property can't be sold until title is cleared. Texas offers several options:
Muniment of Title (Texas Fast Track):
Used when there's a valid will and no unpaid debts (except mortgage). The will itself acts as the deed transfer to beneficiaries. Timeline: 2–4 months. This is the fastest, cheapest option when it applies.
Independent Administration:
Standard probate route when debts exist or assets are complex. The executor receives "Letters Testamentary" and can sell the home. Timeline: 6–12 months.
Affidavit of Heirship:
Used when there's no will and the estate is primarily real estate. Two disinterested witnesses sign an affidavit about the family history. Cheaper than probate, but some title companies hesitate to insure until it's been on record for 5 years.
The Lady Bird Deed (Texas's Secret Weapon)
If your parent still has capacity and wants to plan ahead, a Lady Bird Deed (Enhanced Life Estate Deed) can be powerful.
How it works: Your parent deeds the home to beneficiaries now, but retains full control during their lifetime—including the right to live there, sell it, mortgage it, or revoke the deed entirely.
The Medicaid protection: Upon death, the home passes immediately to beneficiaries outside of probate. Because it doesn't go through probate, it's protected from the Medicaid Estate Recovery Program (MERP), which otherwise can place a claim against the home to recoup medical costs.
This should be set up with an elder law attorney while your parent still has capacity.
Capital Gains: Why Timing Matters
The tax implications of selling can differ by tens of thousands of dollars depending on when the sale happens.
Sale during parent's lifetime:
Capital gain = Sale price minus original purchase price
Example: Parents bought in 1985 for $60,000, selling now for $350,000 = $290,000 gain
Section 121 exclusion: $250,000 (single) or $500,000 (married) of gain is tax-free if it's been their primary residence
For most families: No tax owed
Sale after death (inherited property):
Beneficiaries receive a "stepped-up basis" to fair market value at date of death
Example: You inherit at $350,000 value, sell for $350,000 = $0 capital gain = No tax owed
Strategic insight: If your parent doesn't need the sale proceeds immediately for care, holding the property until death can be the most tax-efficient transfer of wealth—especially if they've been in a care facility for more than 3 years and the home no longer qualifies for the primary residence exclusion.
What to Do When You Need Funds NOW (But the House Isn't Sold)
This is the gap that catches most families off guard.
A spot opens at the assisted living community you want. They need a $5,000 deposit in 48 hours to hold it. Your parent's home is worth $350,000, but it's not sold yet—and traditional sales take 65+ days.
How do you bridge that gap?
Bridge Solutions
Short-Term Respite Care: Many facilities offer 30-day respite stays. This buys time to properly prepare and sell the home without losing the care placement.
HELOC on Parent's Home: A Home Equity Line of Credit provides immediate access to equity. Critical: This must be established before your parent loses capacity. Once they can't sign documents, this option closes.
Move-In Cost Assistance Programs: Some senior-focused home buyers will cover initial move-in costs ($4,000–$8,000) as part of the purchase agreement, advancing funds before closing to secure the facility spot.
Family Bridge Loan: A sibling or family member advances the funds, to be repaid from sale proceeds. Get it in writing to prevent conflicts later.
A Family We Helped: Sherwood's Story
We worked with a gentleman named Sherwood in Burleson whose family was tight on funds right when they needed to secure an assisted living spot. He'd recently suffered a stroke, and his wife was receiving in-home care but declining as well.
Their home was about 15–20 years outdated—it was going to need significant renovation to attract a traditional buyer. They just didn't have the finances to put deposits down and secure the apartment at the assisted living community.
We were able to cover the move-in costs—around $5,000 in community fees and deposits—so they could secure their apartment while we handled the home sale. Within 30 days, Sherwood was settled in, meals provided daily, and his sister in Pennsylvania finally had peace of mind knowing her brother was safe.
For them, speed wasn't necessarily the priority—it was making sure they got a fair price for their home while getting help on the financing side of the transition.
The Emotional Side: What No One Talks About
We've covered the numbers. But selling a parent's home isn't really about numbers, is it?
The Weight of "All the Stuff"
Forty years of accumulated life. The kitchen table where holidays happened. Photo albums from decades you barely remember. Your childhood bedroom, still painted the color you chose in middle school.
You're not just emptying a house. You're dismantling a chapter of your family's story. And you're supposed to do this while also managing medical appointments, coordinating with facilities, and keeping your own life from falling apart.
Permission to Let Go
You don't have to keep everything. Keeping one meaningful item—a single photo, a piece of jewelry, your dad's favorite coffee mug—is enough to honor the memories. The rest is just stuff.
Consider hiring a senior move manager who specializes in this transition. They can help sort, donate, and organize without the emotional weight you're carrying.
The Guilt of "Moving Mom Out"
Let's name it: you probably feel guilty. Like you're betraying your parent. Like you should be able to handle this yourself. Like moving them out of their home is somehow a failure.
It's not.
Getting your parent into a safe environment where they'll have meals, medication management, and people checking on them daily isn't abandonment. It's care. It's love. It's doing the hard thing because you love them too much to let them fall again with no one there to help.
"If you're reading this and feeling guilty about selling your parent's home—take a breath. You're doing the hard thing because you love them. And when families come out the other side, they tell us it feels like a huge weight is off their shoulders. That they can finally focus on what matters: being present with their parent, not managing a house."
Bedford Resources for Families
You don't have to figure this out alone. Here are local resources that can help:
Local Support Services
- Bedford Senior Center: 2817 R.D. Hurt Parkway — socialization, wellness checks, resource referrals
- NETS Transportation: Door-to-door paratransit for residents 65+ in Bedford, Euless, and Hurst (~$3.25/trip)
- Meals on Wheels Tarrant County: Food delivery plus critical daily safety checks
- Tarrant County Area Agency on Aging: Benefits counseling and care coordination
HEB ISD Tax Benefits for Seniors
If your parent is still in the home, they may be eligible for:
$10,000 Over-65 Exemption from HEB ISD
School tax freeze (ceiling): School taxes are frozen at the amount owed when they turned 65
Portability: This tax ceiling can transfer to a new Texas home
Why Bedford Homes Sell
Here's something worth knowing: even if your parent is 85, the buyer is likely a 35-year-old couple targeting HEB ISD schools. Proximity to L.D. Bell High School and Trinity High School is a significant marketing advantage.
Bedford may be an aging community, but it's also a community that young families want to move into. That's good news for your home's value.
Frequently Asked Questions
Can I sell my mom's house if she's in a nursing home?
Yes, but it depends on her mental capacity. If she can understand and sign legal documents, she can sell the home herself. If she's incapacitated, you'll need a valid Power of Attorney that explicitly grants real estate authority. If no POA exists and she's already incapacitated, you may need to pursue court-appointed guardianship.
Can I sell my deceased parents' house without probate in Texas?
Potentially. If there's a valid will and no significant debts, you may qualify for Muniment of Title—a streamlined process that admits the will as evidence of title transfer without full probate administration. If there's no will, an Affidavit of Heirship may work, though some title companies hesitate to insure until it's been on record for several years. Consult with a probate attorney to determine the best path.
Do you have to pay taxes on an inherited house in Texas?
In most cases, minimal or no taxes are owed. When you inherit property, you receive a "stepped-up basis" to the fair market value at the date of death. If you sell for that value, your capital gain is zero. Texas also has no state income tax, so there's no state-level tax on the gain either.
How do I sell inherited property with multiple owners (siblings) in Texas?
All owners must agree to the sale and sign the deed. If siblings disagree about selling, you may need to pursue a partition action through the courts, which forces a sale and divides proceeds. This is expensive and damages family relationships—try to reach agreement through mediation first.
How much do cash buyers usually offer?
Most cash investors use the "70% rule": (After Repair Value × 70%) minus estimated repair costs. For a Bedford home worth $385,000 after renovation, with $60,000 in needed repairs, expect offers around $209,000–$230,000. However, senior-focused buyers who understand the full picture may offer more, especially for homes that don't require major structural work.
Is it better to sell your house to a cash buyer?
It depends on your specific situation. Cash sales make sense when you need speed (care placement is urgent), when the home has issues that disqualify it from traditional financing, when you're managing from out of state, or when the cost of holding the home during a traditional sale would exceed the price difference. For homes in good condition where families have time and flexibility, traditional sales typically net more.
How quickly do assisted living spots fill up?
High-quality facilities in the Bedford area often have waitlists. When a spot opens, families typically have 24–48 hours to commit financially. This is why having access to bridge funds—through a HELOC, family loan, or move-in assistance program—is so important. You don't want to lose a good placement because you're waiting for a home sale to close.
The Bottom Line
Selling your parent's Bedford home to pay for assisted living is one of the hardest things you'll do. It's emotional. It's complicated. And there's no one-size-fits-all answer.
But you have more options than you think. Whether your family needs maximum value from a traditional sale, the speed and certainty of a cash offer, or something in between—understanding your choices is the first step toward making a decision you can feel good about.
What matters most isn't the house. It's getting your parent into a safe, appropriate environment where they'll be cared for. The house is just the tool that makes that possible.
When You're Ready
If you want to understand what your parent's Bedford home is actually worth—and walk through all your options with someone who's helped hundreds of DFW families through this exact transition—we're here.
No pressure. No obligation. Just clarity.