Running Out of Savings Paying for In-Home Caregivers: What Comes Next
Key Takeaways
- Agency in-home care in DFW costs $25–$35/hour — at 40 hours per week, that's $4,000–$5,600/month, and 24/7 coverage runs $16,800–$23,520/month, depleting a median $164,000 in savings within 24–36 months.
- DFW families facing savings depletion have four realistic paths: Texas Medicaid (STAR+PLUS), transitioning to assisted living or memory care, selling the home for immediate equity, and accessing overlooked benefits like VA Aid & Attendance.
- DFW assisted living averages $5,332/month — significantly less than 24/7 in-home agency care — and a $415,000 home sale can net approximately $302,750, funding roughly 4–5 years of assisted living.
- Early action matters: families who begin Medicaid planning 12–18 months before anticipated need avoid disqualification penalties, and cash home sales can close in as few as 7–10 days when care transitions are urgent.
- Trust Sage Senior Support for compassionate, no-pressure guidance through every step of the senior care transition — visit Sage Senior Support to explore your family's options today.
When In-Home Care Savings Run Out, What Are Your Options?
When savings are depleted, DFW families typically have four main paths forward: exploring Medicaid eligibility, transitioning to assisted living or memory care, selling the home to fund care, or accessing overlooked benefits like VA Aid & Attendance. The key is acting before the crisis hits, not after. Each option has different timelines, financial impacts, and emotional considerations—and the right choice depends on your parent's care needs, health trajectory, and family circumstances.
Understanding these pathways now, before savings are completely gone, gives you time to make a calm, informed decision rather than a desperate one.
Sage Senior Support
Free Consultation & Cash Offer in 24 Hours
Core Service Programs:
- Cash Home Buying for families needing to sell a parent's home fast to fund senior care
- Senior Care Resources with personally-vetted community partners to assist your family in the transition for your loved one
- Care Funding Discovery Home sell options for Texas Medicaid, VA benefits, long-term care insurance, and bridge financing
Why Choose Sage Senior Support:
- ✓ Trusted by customers with a perfect 5.0-star Google rating across 26 verified reviews
- ✓ Founded by someone who's lived this transition — twice (2013 & 2024)
- ✓ 100+ DFW families guided through senior care transitions
- ✓ Cash offers same day — close in as few as 10 days
- ✓ Zero commissions, zero closing costs, no repairs needed
- ✓ Connection to free care placement — agents paid by the community, not your family
- ✓ Locally owned in Grapevine, TX — serving the entire DFW metroplex
The Reality: How Fast In-Home Care Costs Deplete Savings
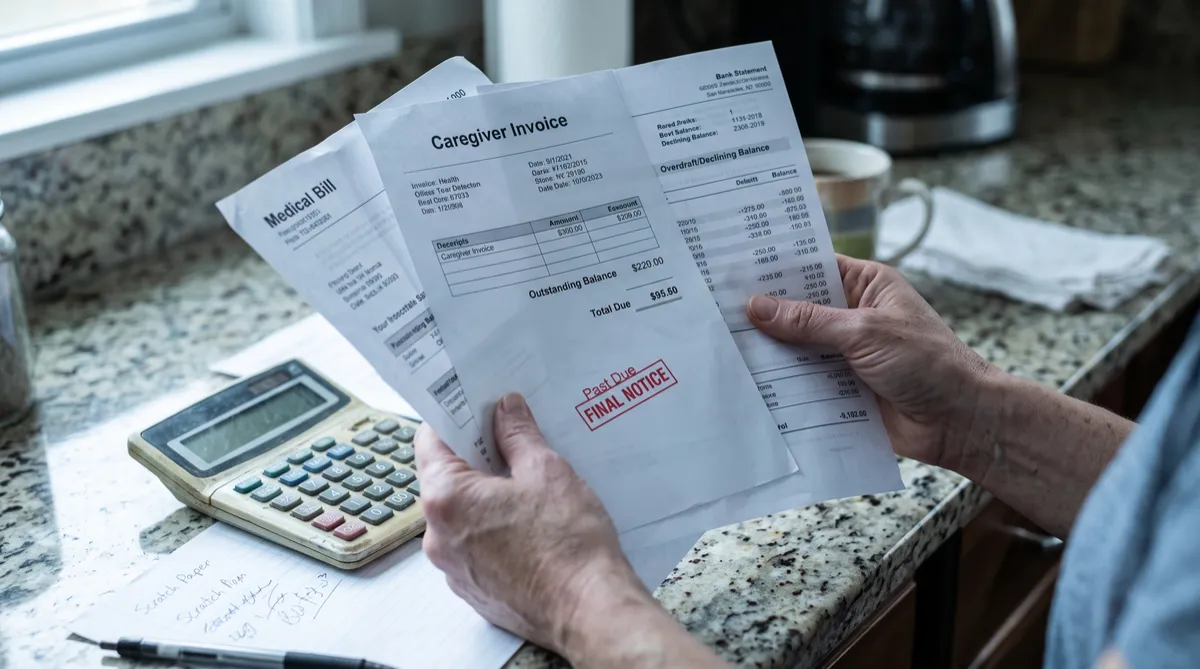
The math is sobering, and most families don't see it coming until they're already in the middle of it. Agency-employed caregivers in DFW cost between $25 and $35 per hour. At 40 hours per week — which covers daytime support but leaves nights and weekends unaddressed — that's $4,000 to $5,600 every month. When care needs escalate to round-the-clock coverage, agency costs jump to $16,800–$23,520 per month. That's not a typo.
The Federal Reserve's data shows median retirement savings for households aged 65–74 sits around $164,000. At consistent DFW in-home care rates, that nest egg is gone in 24 to 36 months. And that's before accounting for hidden costs that families routinely underestimate: overtime and weekend surcharges (caregivers typically earn 1.5x for holidays), last-minute replacement fees, medical supplies, home modifications like grab bars and ramps, and the occasional ER co-pay when something goes wrong at home. These extras add 20–40% to stated hourly rates. In-home care costs also rise 3–5% annually, outpacing general inflation and quietly eroding your purchasing power every year.
If you're watching the bank balance drop month after month and feeling the panic rise, you're not doing anything wrong. This is one of the most common financial crises DFW families face — and it has real solutions. Use our senior care cost calculator to model how long your current savings will last at today's DFW rates.
You're Not Alone — This Is a Common Crisis Point
Thousands of DFW families face this exact moment: watching savings deplete month after month, feeling the panic rise, and wondering what comes next. The emotional weight of this decision is real, and your guilt about potentially moving your parent or selling their home is completely normal.
Path 1: Medicaid Long-Term Care (STAR+PLUS) in Texas
Texas Medicaid's long-term care program — known as STAR+PLUS — is often the first thing families think of when savings run low. But the eligibility rules are strict, and the timing of your application matters enormously.
As of January 2026, the income limit for an individual applicant is $2,982 per month. The countable asset limit is $2,000 — though the primary residence is exempt up to $752,000 in equity, provided certain conditions are met (such as a spouse living in the home or the applicant intending to return). STAR+PLUS waiver programs can cover in-home care, assisted living, and memory care services, making this a meaningful funding source for families who qualify.
The critical mistake families make is waiting too long to start the process. Medicaid planning must begin well before savings are exhausted — ideally 12–18 months in advance. Improper timing or asset transfers made too close to the application date can trigger penalty periods that delay eligibility. Selling the home, for example, converts an exempt asset into countable cash, which can push your parent over the $2,000 asset limit and require a spend-down before Medicaid kicks in. An elder law attorney can help you structure assets strategically and avoid these costly missteps. For a deeper look at how home equity intersects with Medicaid eligibility, read our guide on Medicaid planning to protect home assets.
Consult an Elder Law Attorney Before Making Major Moves
Whether you're considering Medicaid, selling the home, or restructuring assets, an elder law attorney can help you avoid costly mistakes. Many offer free initial consultations and can save you thousands by timing decisions strategically and protecting assets from unnecessary spend-down.
Path 2: Transition to Assisted Living or Memory Care
Here's a comparison that surprises most families: DFW assisted living averages $5,332 per month. Memory care runs $6,673–$7,100 per month. Compare that to 24/7 in-home agency care at $16,800–$23,520 per month, and the math shifts dramatically in favor of a facility once your parent needs consistent daily support or around-the-clock supervision.
Facility-based care also bundles costs that families pay separately at home: meals, activities, emergency response systems, medication management, and 24-hour staff coverage. When you add up what you're actually spending on in-home care — the agency fees, the medical supplies, the home modifications, the weekend surcharges — a quality assisted living community often delivers more comprehensive care for less money.
The transition typically becomes advisable when daily care needs exceed 6–8 hours, when 24/7 supervision is required, or when safety concerns (frequent falls, wandering, medication errors) can no longer be managed at home. Many DFW facilities also accept Medicaid, offer financial assistance programs, or use sliding-scale pricing — options worth exploring before assuming a facility is out of reach. For a side-by-side breakdown of costs and care levels, see our memory care vs. in-home care cost comparison.
Path 3: Selling the Home to Fund Senior Care in DFW
For most DFW seniors, the home is their largest remaining asset — and often the most practical funding source when savings are gone. The DFW metro median home value sits around $415,000 in 2026. After typical selling costs, a family can realistically net approximately $302,750 from a traditional sale. At the current DFW assisted living average of $5,332 per month, that proceeds figure covers roughly 4.7 years of care. For memory care at $7,000 per month, it funds approximately 3.6 years.
The timeline is where families often get caught. Traditional MLS sales in DFW currently take 60–105 days from listing to closing — too slow when a care transition is urgent and monthly bills are mounting. Cash sales to companies like Sage Senior Support close in 7–10 days, providing immediate access to home equity without repairs, showings, or commission fees. The trade-off is a somewhat lower net proceeds compared to a traditional sale, but when care needs are escalating and savings are depleted, the speed and certainty of a cash sale frequently outweighs the difference.
Home sale proceeds can also serve as a bridge — funding care during the gap between savings depletion and Medicaid eligibility, which can take months to establish. Our real estate services page explains how we work with families to make this process as straightforward as possible, including our no-commission, no-repair approach. You can also read our detailed guide on how to sell a parent's home to pay for senior care for a full walkthrough of the mechanics and emotional considerations involved.
Path 4: Overlooked Benefits — VA Aid & Attendance and Other Resources
This is the path most families don't know exists until someone tells them. If your parent served in the military, they may qualify for VA Aid & Attendance — a pension benefit that pays up to $2,300 per month for a single veteran or $2,727 per month for a married veteran (2024 rates). Surviving spouses of veterans may qualify for up to $1,478 per month. That's a substantial monthly subsidy that can meaningfully extend your care-funding runway.
The benefit is widely underutilized because families simply don't know about it, or they assume their parent's service doesn't qualify. The application process is detailed and requires documentation of military service, medical need, and financial eligibility — but VA-accredited agents can guide you through it at no cost. The VA's net worth limit for pension benefits from December 2025 through November 2026 is $163,699, so many families who assume they're "too wealthy" to qualify may actually be eligible.
Beyond VA benefits, two other options are worth evaluating: life insurance policy loans, which allow fixed-rate borrowing against a policy's cash value without affecting credit or triggering a taxable event, and reverse mortgages, which allow homeowners 62 and older to access home equity without selling — though reverse mortgages carry fees and complexity that warrant careful review with a financial advisor. Our guide on VA Aid & Attendance benefits for assisted living covers eligibility and the application process in detail. For a comprehensive look at all funding options, download our guide to paying for long-term care.
The Cost of Waiting: Why Early Decisions Matter
Every family we talk to wishes they had started this conversation sooner. When decisions get delayed until a fall, a hospitalization, or a medical emergency forces the issue, options narrow fast. Crisis-driven placements mean less time to compare facilities, less leverage in negotiations, and higher total costs over the care journey.
Prolonged in-home care at escalating rates also exhausts savings faster than a planned facility transition would have. Adult children who delay consistently report higher rates of caregiver burnout, stress, and their own health decline — the emotional and physical toll of managing an unsustainable situation compounds over time. And Medicaid planning started too late can trigger disqualification penalties that leave families without a safety net precisely when they need it most.
The families who navigate this best are the ones who start planning 12–18 months before they think they'll need to act. That window gives you time to explore all four pathways calmly, consult the right professionals, and make a decision that reflects your parent's care needs and your family's values — not a decision made under duress at 11 p.m. after a crisis call. Read our guide on creating an aging plan before a crisis to understand what proactive planning actually looks like in practice.
Don't Wait Until the Crisis Hits
Families who delay decisions until a fall, hospitalization, or emergency often face limited options, higher total costs, and rushed placements they later regret. Early planning — even 12–18 months before anticipated need — gives you time to explore all four pathways calmly and choose the best fit for your family.
Why Sage Senior Support Is the Right Choice for DFW Families Facing Care Transitions
Sage Senior Support has earned a perfect 5.0-star Google rating across 26 verified reviews — not by being the biggest company in DFW, but by treating every family the way we'd want our own family treated. Our founder navigated senior care transitions twice in his own family, in 2013 and again in 2024, so when you call us and say "I don't even know where to start," we mean it when we say we understand exactly how that feels.
We've guided more than 100 DFW families through care transitions, and our approach starts the same way every time: we ask how Mom or Dad is doing before we ever talk about the house. From there, we connect families to our network of trusted placement agents, elder law attorneys, and financial advisors who can help explore all four pathways — Medicaid, facility transitions, home sales, and overlooked benefits like VA Aid & Attendance. Our senior transition concierge services are built around this whole-family approach.
When selling the home is the right move, we deliver cash offers within 24–48 hours and can close in as few as 10 days — no repairs, no commissions, no closing costs. That speed matters when care costs are mounting and every week counts. And as a locally owned company based in Grapevine, TX, we understand the specific market dynamics, care costs, and family pressures across Dallas and Tarrant counties in a way that national buyers simply don't.
Schedule a Free Consultation with Sage Senior Support — and get clarity on every option available to your family, with no pressure and no obligation.
Frequently Asked Questions
What happens to my parent's care if we run completely out of money before Medicaid kicks in?
This gap is one of the most stressful situations DFW families face, and it's more common than most people realize. If savings are depleted before Medicaid eligibility is established, your parent may face a temporary care funding gap. This is exactly why accessing home equity early (Path 3) or securing VA benefits (Path 4) can serve as a critical bridge. Texas does have emergency Medicaid programs that may cover urgent care needs during the waiting period, but eligibility rules are strict. Work with an elder law attorney to time your Medicaid application strategically — ideally starting the process 12–18 months before you anticipate needing it, not after the savings account hits zero.
Is selling Mom's house the only way to fund care when savings are gone?
No — but for many DFW families, it's the most practical option because home equity is typically the largest remaining asset. Before making any decisions, explore all four pathways: Medicaid eligibility through STAR+PLUS, a transition to assisted living or memory care that may actually cost less than escalating in-home care, VA Aid & Attendance benefits if your parent served in the military, and life insurance policy loans if a permanent policy exists. A comprehensive financial assessment with an elder law attorney or financial advisor often reveals options families hadn't considered. The goal is to make an informed decision, not a rushed one.
How quickly can we access money from selling the house if we're in a care crisis?
Traditional MLS sales in today's DFW market take 60–105 days from listing to closing — far too slow when care costs are mounting and savings are gone. Cash sales to companies like Sage Senior Support close in as few as 7–10 days, providing immediate access to home equity when a care transition is urgent. The trade-off is a somewhat lower net proceeds compared to a traditional sale, but in a genuine care crisis, the speed and certainty of a cash sale frequently outweighs that difference. There are no repairs required, no commissions, and no waiting for a buyer to secure financing.
What are the first steps to take when we realize we can't afford in-home caregivers anymore?
Start with an objective assessment of your parent's current care needs — consult their physician or a geriatric care manager for an updated recommendation on what level of care is actually required. Second, review all financial options: calculate how long remaining savings will last at current care costs, explore Medicaid eligibility with an elder law attorney, research VA benefits if applicable, and get a home valuation if selling is on the table. Third, research assisted living and memory care facilities in DFW to compare costs and services — you may find that a facility transition is both more affordable and safer than continuing to escalate in-home care. Finally, have an honest family conversation about priorities: safety, cost, and your parent's preferences.
What makes Sage Senior Support different from other home buyers or care advisors?
Sage Senior Support starts every conversation by asking how your parent is doing — not by talking about the house. We've earned a perfect 5.0-star Google rating across 26 verified reviews by connecting families to trusted placement agents, elder law attorneys, and financial advisors who help explore all four pathways: Medicaid, facility transitions, home sales, and overlooked benefits. Our founder navigated senior care transitions twice in his own family, so we understand the emotional weight and financial complexity you're carrying. As a locally owned Grapevine company serving all of DFW, we know the unique market dynamics and care costs in this region — and we deliver cash offers within 24–48 hours with closing in as few as 10 days when urgency matters. Ready to explore your options? Schedule a Free Consultation with our team today.
Running Out of Savings for In-Home Care? Let's Find Your Family's Path Forward.
You don't have to figure this out alone. Whether you're weighing Medicaid, considering a facility transition, or wondering what your parent's home could do for their care funding, we'll walk through every option with you — no pressure, no jargon, just honest answers from people who've been in your shoes.
Our consultations are free, our cash offers come within 24 hours, and we've helped more than 100 DFW families find clarity in exactly this moment.
Service availability, benefit eligibility, and home valuations depend on individual circumstances and current market conditions. This article is for informational purposes only and does not constitute medical, legal, or financial advice. Contact us for personalized guidance specific to your family's situation.