Quick Sale vs Market Value for Distressed Homeowners in Euless TX
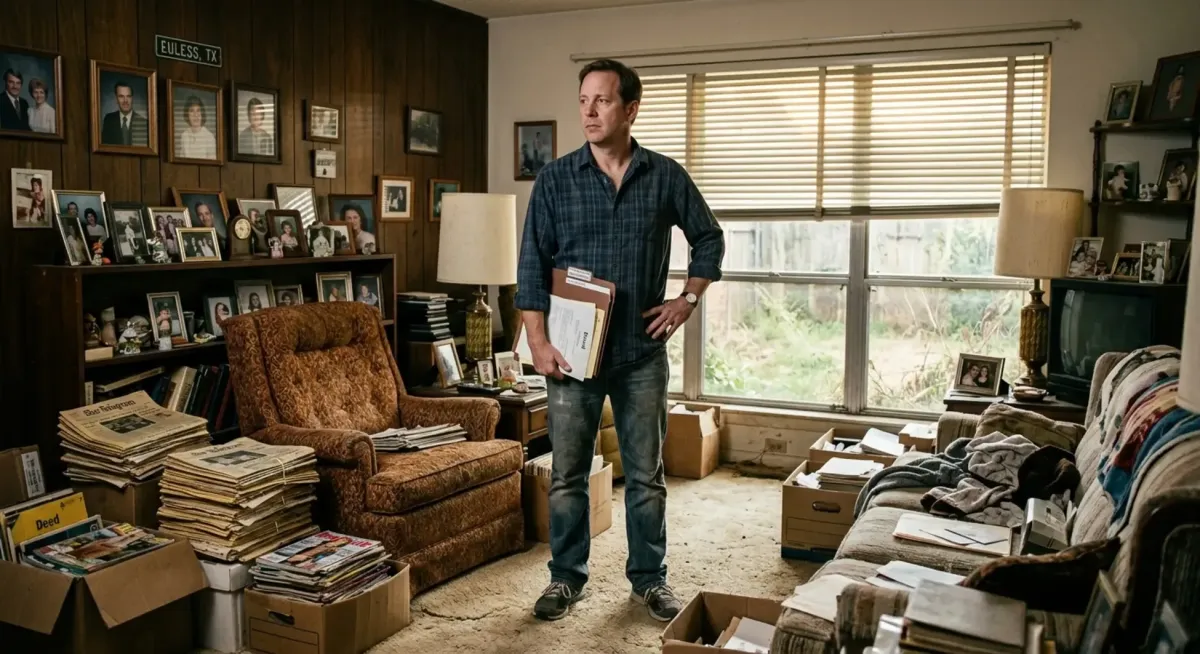
You're standing in your mom's 1985 ranch house in Euless. The carpet is the original harvest gold. The HVAC unit has been limping along for three summers. There's a crack running along the back foundation wall that the inspector flagged two years ago — and nobody did anything about it. And somewhere across town, a memory care facility is waiting on a deposit that's due in less than 30 days.
You've been on the phone with your siblings. One says, "List it — we'll get more money." Another says, "Just take the cash offer and be done with it." You're standing in the middle, feeling the weight of both arguments, and a quiet guilt that whispers: what if we leave money on the table?
Here's what nobody tells you in that moment: both paths have real costs. The "higher price" of a traditional listing isn't always higher when you subtract commissions, repair credits, carrying costs, and the months of uncertainty while your parent's care needs don't pause for the real estate market. And the "lowball" cash offer isn't always as low as it looks once you run the actual numbers.
The right choice depends on what your family actually needs right now — not what sounds best in theory. This guide is here to help you figure that out, clearly and without pressure.
Key Takeaways
- Quick cash sales typically offer 70–85% of a home's post-renovation value — but sellers avoid commissions, repairs, carrying costs, and months of uncertainty that can significantly narrow the net proceeds gap.
- Distressed homes in Euless — especially those with foundation, roof, or HVAC issues — face 60–120+ days on market with traditional listings, plus inspection credits that can reduce the sale price by 5–15%.
- Tarrant County's clay soil makes foundation problems one of the most common and expensive issues for Euless homes built in the 1970s–1990s, directly impacting both sale price and buyer pool.
- DFW long-term care costs in 2026 run $4,500–$7,500+ per month. Delays in selling can cost $3,000–$9,000+ in unreimbursed care expenses — sometimes more than the difference between sale options.
- Texas Medicaid (STAR+PLUS) requires asset spend-down for long-term care eligibility. Home sale timing directly impacts Medicaid access and can mean the difference between covered and out-of-pocket care.
- Legitimate cash buyers are transparent about offer calculations, provide proof of funds, allow adequate option periods, and never use high-pressure tactics. Knowing the red flags protects your family.
- This is a values-based decision, not just a financial one. The "right" path is the one that aligns with your family's timeline, care needs, emotional capacity, and definition of success.
The Real Question Distressed Homeowners in Euless Are Asking
Most families come into this decision with a simple assumption: quick sale equals a lowball offer, and traditional listing equals maximum value. That framing feels logical, but it's incomplete — and acting on it without the full picture can cost your family tens of thousands of dollars and months of unnecessary stress.
The real question isn't "which path gets me more money?" It's "which path gets me what I actually need, given everything that's happening right now?" Those are very different questions, and they lead to very different answers depending on your family's specific situation.
When you're managing a parent's care transition — coordinating with facilities, handling medical appointments, sorting through decades of belongings — the real cost of waiting isn't just the difference in sale price. It's the carrying costs that accumulate every month the house sits empty. It's the repair credits buyers demand after inspections. It's the emotional burden of managing showings while also managing a care crisis. And it's the delayed access to funds that your parent needs right now. Understanding how families are funding senior living costs reveals just how central the home sale timeline is to the entire care funding picture.
Euless homeowners face some specific pressures that make this decision more complex than it might be in other markets. The housing stock here skews older — many homes were built between the 1970s and 1990s, which means foundation issues, aging HVAC systems, and deferred maintenance are the norm rather than the exception. Add to that the urgency of a care transition deadline, and you have a situation where the "wait for top dollar" strategy carries real financial and emotional risks that don't show up in the listing price.
This decision is personal. It depends on your timeline, your parent's care needs, what the house actually needs to be market-ready, and what "success" looks like for your family. There's no universal right answer. But there is a way to think through it clearly — and that's what this guide is for.
You're Not Alone in This Dilemma
Thousands of families in Euless and across DFW face this exact decision every year. The guilt about "leaving money on the table" is real, but so is the relief of moving forward quickly. Both feelings are valid — and both deserve to be taken seriously when you're making this choice.
Understanding the Euless Market: Why Your Home's Condition Matters More Than You Think
Before you can make a smart decision about how to sell, you need to understand what you're actually working with in the Euless market — and why a distressed home here faces challenges that don't apply to move-in ready properties.
Euless sits in the heart of the Mid-Cities area of Tarrant County, with a population of approximately 55,000 residents. Its central location near DFW Airport is a genuine asset, and the community has maintained stable homeownership rates over time. But a significant portion of the housing stock was built between the 1970s and 1990s — and those homes are now 35 to 55 years old. That age range means buyers are looking at aging roofs, original HVAC systems, outdated electrical panels, and — critically — the foundation issues that Tarrant County's expansive clay soil is notorious for producing.
The median home sale price in Euless has generally ranged from the high $300,000s to the low $400,000s. But distressed or as-is homes — those needing significant repairs or updates — typically sell at a discount of 15% to 30% below comparable move-in ready homes, according to data from the Texas Real Estate Research Center and MetroTex MLS. That discount isn't arbitrary. It reflects the real cost buyers absorb when they take on a home that needs work.
Days on market tell a similar story. Move-in ready homes in Euless typically sell within 15 to 30 days in a normal market. Distressed homes — those with deferred maintenance, structural issues, or dated systems — can sit for 60 to 120 days or longer. That extended timeline has direct financial consequences for sellers, which we'll quantify in detail later. For families considering maximizing home value before a senior transition, understanding these market dynamics is the essential starting point.
Seasonal demand also matters. Spring (March through May) and early fall (September through October) see peak buyer activity in Tarrant County. If your timeline doesn't align with peak season, you may face deeper price concessions — or a longer wait that compounds carrying costs. Cash buyers and investors, by contrast, are active year-round and don't follow seasonal patterns.
Why Foundation and Major Systems Are Deal-Breakers in Euless
Foundation problems deserve special attention because they're so common in this area and so consequential for sale outcomes. Tarrant County's clay soil expands and contracts dramatically with moisture changes — and that movement, over decades, causes foundations to shift, crack, and settle unevenly. For a home built in 1978 or 1985, there's a meaningful chance the foundation has some degree of movement that will show up on an inspection report.
Foundation repair costs in North Texas typically run from $5,000 to $25,000 or more, depending on the severity of the issue and the repair method required. That single line item can dramatically reduce your buyer pool — many buyers using conventional financing won't qualify for a loan on a home with unresolved foundation issues, and those who can afford to address it will demand a significant credit or price reduction.
Roof replacement runs $8,000 to $15,000 or more for a typical Euless home. HVAC systems in older homes are often 20+ years old and nearing the end of their functional life — replacement costs range from $5,000 to $8,000 or more. These aren't cosmetic issues. They're structural and mechanical, and they trigger serious buyer hesitation, lender scrutiny, and inspection-driven negotiation that can derail deals entirely.
When you're evaluating your options, the condition of these major systems isn't just a repair estimate — it's a filter that determines which buyers will even consider the home, and on what terms.
Quick Sale (Direct Cash Purchase): The Fast Path Explained
A quick cash sale gets a bad reputation because of the bad actors in the space — the unsolicited mailers, the cold calls targeting seniors, the vague offers with no explanation. But when done with a reputable buyer, a direct cash purchase is a legitimate, transparent transaction that solves a real problem for families in urgent situations. Understanding exactly how it works removes the mystery and lets you evaluate it on its actual merits.
The timeline is the most obvious advantage: from first contact to closing typically runs 14 to 30 days. There are no showings, no open houses, no waiting for buyer financing to clear, no appraisal contingencies. You sign a contract, the buyer conducts their inspection during the option period, and you close. Funds are typically wired within one to two business days after closing — which is critical when you're waiting on a care facility deposit or need to cover the first month's memory care costs.
For families exploring this path, our guide on selling parents' home as-is to fund senior care walks through how the process works in the DFW area and what families can realistically expect.
The Offer Breakdown: Where Your Money Goes (and Doesn't)
A legitimate cash buyer calculates their offer using a straightforward formula. They start with the After Repair Value (ARV) — what the home would sell for if it were fully renovated and move-in ready. They then subtract their estimated repair costs, their profit margin, and their transaction costs. What's left is your offer price.
Typical offers run 70% to 85% of ARV. So if your home would be worth $450,000 move-in ready, and it needs $40,000 in repairs, a cash buyer might offer somewhere in the range of $315,000 to $350,000. That spread exists because the buyer is absorbing the risk, the repair costs, the holding costs during renovation, and their profit margin. A reputable buyer will show you this math — ARV, estimated repairs, their margin — so you understand exactly how they arrived at the number.
What the seller avoids in a cash sale is equally important to understand. There's no agent commission (typically 5–6% of sale price), no staging costs, no repair credits demanded after inspection, no carrying costs accumulating over months, and no professional cleanout expense. For a $350,000 cash offer, avoiding $21,000 in commissions alone changes the net proceeds picture significantly.
Red Flags: How to Spot a Predatory Quick Buyer
Not every cash buyer is operating ethically, and families in distress are unfortunately a target for predatory investors. Knowing the warning signs protects you from being taken advantage of during an already difficult time.
High-pressure tactics are the clearest red flag. Legitimate buyers give you time to review offers, consult with family members, and ask questions. If someone tells you "this offer expires in 24 hours" or "you need to decide today," that's a manipulation tactic, not a business practice. Walk away.
Refusal to explain the offer calculation is another warning sign. You should understand exactly how the buyer arrived at their number — ARV, repair deductions, margin. If they won't show you the math, they're not operating transparently.
Requests for upfront fees or deposits are illegal in Texas. Real buyers don't ask for money before closing. Unsolicited offers and cold calls — especially those targeting seniors — are a common pattern among predatory investors. And if an offer changes significantly near closing, that's a classic bait-and-switch. Legitimate buyers lock in terms and honor them. You can find more detail on vetting buyers in our guide to cash home buyer scams in DFW and how to vet them.
Curious What Your Home Might Be Worth in a Cash Sale?
If you're exploring a quick sale and want to understand what your home might be worth with no obligation, we can help you get a clear picture of your options — without pressure and without a sales pitch.
Traditional Market Listing: The Higher Price, Higher Cost Path
A traditional listing is the path most families default to, because "listing at market value" sounds like the responsible choice. And sometimes it is. But for distressed homes in Euless, the gap between the gross sale price and the actual net proceeds that land in your pocket is often much larger than families expect — and the process is far more demanding than it looks from the outside.
For a distressed home in Euless, realistic timelines run 60 to 120 days or longer from listing to closing. That's not a worst-case scenario — it's a typical outcome for homes that need significant work, because the buyer pool is smaller and the financing hurdles are higher. Move-in ready homes in the same market might sell in 30 to 45 days. The difference matters enormously when you're carrying costs every month.
The seller costs in a traditional listing add up quickly. Agent commissions typically run 5–6% of the sale price. Closing costs add another 1–3%. Inspection credits — the repair concessions buyers demand after their inspector identifies issues — commonly run 5–15% of the sale price on distressed homes. Carrying costs (property taxes, insurance, utilities on a vacant or occupied home) run $800 to $1,500 or more per month. Staging and professional cleanout add $2,000 to $5,000. It's worth understanding how the effects of the NAR settlement on real estate commissions have changed how buyer agent compensation works — since 2025, buyer agent commissions are negotiated directly between buyers and their agents rather than being listed on the MLS, which has shifted some dynamics in how sellers structure concessions.
The Hidden Costs That Eat Into Your Net Proceeds
Let's be specific about what "hidden costs" actually means in practice, because these numbers don't always get laid out clearly when families are deciding how to sell.
Carrying costs alone can be staggering. A $400,000 home in Tarrant County might cost $800 to $1,500 or more per month in property taxes, homeowner's insurance, utilities, and basic maintenance. Over a 90-day listing period, that's $2,400 to $4,500 in costs before you've sold anything. Over 120 days, it's $3,200 to $6,000. These aren't hypothetical — they're real expenses that reduce your net proceeds dollar for dollar.
Inspection repair credits are another major variable. When a buyer's inspector identifies foundation movement, an aging roof, or an HVAC system past its useful life, the buyer will typically request a credit or price reduction. On a distressed Euless home, these credits commonly range from 5% to 15% of the sale price — that's $20,000 to $60,000 on a $400,000 home. You can push back on these requests, but doing so risks losing the buyer entirely and starting the process over.
Price reductions compound the problem. If a distressed home doesn't sell within 30 to 45 days, most agents will recommend a price reduction to generate new interest. Cumulative reductions of 10% to 20% are common for homes that sit on the market for 90 days or more. Each reduction chips away at the "higher price" that made traditional listing seem attractive in the first place.
The Emotional and Logistical Burden of Listing
The financial costs are measurable. The emotional and logistical costs are harder to quantify but just as real — and for families already managing a care transition, they can be genuinely overwhelming.
Showings require the home to be clean, accessible, and vacant on short notice. If you're also coordinating your parent's move to assisted living, managing medical appointments, and handling the emotional weight of the transition, keeping a house show-ready for 60 to 120 days is an enormous additional burden. Every showing is an interruption. Every offer negotiation adds stress. Every inspection report reopens difficult conversations.
And through all of it, there's no guarantee of closing. Buyer financing can fall through. Appraisals can come in below the agreed price. Contingencies can give buyers an exit at any point. The uncertainty compounds the emotional burden in ways that don't show up in any spreadsheet — but they're very real for families who are already stretched thin.
Side-by-Side Comparison: Quick Sale vs Traditional Listing in Euless
Now let's put both paths side by side across the dimensions that actually matter for distressed homeowners in Euless. For a deeper look at how these two paths compare on timeline and convenience specifically, our analysis of cash buyers vs traditional sale timeline and convenience in DFW goes into additional detail.
| Factor | Quick Cash Sale | Traditional Listing |
|---|---|---|
| Timeline to Close | 14–30 days | 60–120+ days for distressed homes |
| Certainty of Closing | High — reputable buyers, clear contracts | Lower — financing, appraisals, contingencies |
| Commissions | None | 5–6% of sale price |
| Repairs Required | None — sold as-is | Inspection credits 5–15% of sale price |
| Carrying Costs | Minimal — closes quickly | $800–$1,500+/month for 60–120 days |
| Emotional Burden | Low — one decision, one closing | High — showings, negotiations, uncertainty |
| Funds Available | 1–2 business days after closing | At closing, 60–120+ days out |
| Gross Sale Price | Lower (70–85% of ARV) | Potentially higher — but with concessions |
Net Proceeds Comparison: A Real Example
Let's run the actual numbers on a realistic Euless scenario, using figures based on Tarrant County market data.
Quick sale scenario: Cash offer of $350,000. The seller avoids approximately $21,000 in agent commissions, $5,000 in repair costs or credits, $3,000 in carrying costs (closing in 21 days), and $2,000 in cleanout and staging. Estimated net proceeds: approximately $319,000.
Traditional listing scenario: List at $450,000, sell for $430,000 after inspection concessions and buyer negotiations. Costs include approximately $25,800 in commissions, $5,000 in closing costs, $5,000 in repairs or credits, $5,000 in carrying costs over 90 days, and $3,000 in cleanout and staging. Estimated net proceeds: approximately $386,200.
The difference is approximately $67,000. That's real money, and it matters. But this scenario assumes the traditional listing sells at a strong price, quickly, without major concessions beyond the initial estimate. In reality, distressed homes in Euless often face deeper inspection credits, longer timelines, and price reductions that compress that gap significantly. Variables like how quickly the home sells, whether the appraisal comes in at contract price, and the extent of repair demands can shift the math dramatically.
The question isn't whether $67,000 is worth pursuing. It might be. The question is whether your family's specific situation — timeline, care needs, home condition, emotional capacity — makes that pursuit realistic and sustainable.
The Math Doesn't Always Tell the Whole Story
Yes, a traditional listing might yield a higher gross sale price. But when you subtract commissions, repairs, carrying costs, and the emotional toll of 60–120 days of uncertainty, the net difference often shrinks dramatically. And that doesn't account for the value of peace of mind and being able to focus on your parent's care during one of the hardest seasons your family will face.
When Quick Sale Makes Sense
A quick cash sale is often the better path when your family faces an urgent need for funds — an assisted living deposit, a memory care first month, medical bills due within 30 to 60 days. It's also the clearer choice when the home requires substantial repairs: if foundation, roof, or major systems need work that exceeds 10% of the home's value, the repair credit demands from traditional buyers will significantly erode the price advantage.
Caregiver burnout is real. If you've been managing your parent's care for months or years, you may simply not have the emotional capacity to also manage a 90-day listing process. That's not weakness — it's an honest assessment of your limits. A quick sale can give you back the mental space to focus on what matters most. For families dealing with inherited properties where multiple heirs need a clean, fast resolution, a cash sale eliminates the family conflict that often accompanies listing decisions. You can also explore what the Euless TX cash home buyer process looks like specifically for your area.
When Traditional Listing Makes Sense
Traditional listing is the stronger choice when the home needs only minor cosmetic updates and is structurally sound — no foundation issues, a relatively new roof, functioning HVAC. When the seller has six months or more and can comfortably absorb carrying costs without financial strain, the time investment in a traditional listing is more justifiable. If the market strongly favors sellers of dated homes in Euless — low inventory, high demand — the price premium may be achievable without the typical concessions. And if net proceeds are the absolute highest priority and the seller has the emotional support and time to manage the process, listing traditionally can yield the best financial outcome.
The True Cost of Waiting: Why Delayed Decisions Cost More Than You Think
One of the most common patterns we see is families waiting too long to act — hoping the situation will stabilize, waiting for a better time, or simply feeling too overwhelmed to make a decision. It's completely understandable. But the financial and emotional cost of that delay is often larger than the difference between sale options.
A vacant $400,000 home in Tarrant County can cost $800 to $1,500 or more per month in property taxes, homeowner's insurance, utilities, and basic maintenance. That's $9,600 to $18,000 or more per year — just to keep the lights on and the insurance current. Every month of delay is money that could have been funding care.
Deferred maintenance compounds the problem exponentially. A minor roof leak that costs $500 to address today becomes $5,000 in water damage if left alone for six months. A small foundation crack that needs $3,000 in pier work now can become a $15,000 structural repair if the underlying drainage issue isn't resolved. The home doesn't stay in the same condition while you're deciding — it deteriorates, and the cost of that deterioration falls on you. Understanding what happens if you wait too long to sell a house lays out these consequences in stark financial terms.
The care funding gap is perhaps the most painful cost of waiting. Families often wait three to six months after a health crisis before initiating a home sale. That delay can cost $3,000 to $9,000 or more in carrying costs alone — plus the out-of-pocket care expenses that accumulate while the home sale is still pending. In 2026, DFW long-term care costs run $4,500 to $6,500 per month for assisted living, $5,500 to $7,500 for memory care, and $6,000 to $8,500 for skilled nursing, according to Genworth Cost of Care data and local provider estimates. Home equity from a $400,000 home can be consumed within four to seven years of care at these rates. Every month of delay in accessing those funds is a month of care that comes from somewhere else — or doesn't come at all.
There's also the market value risk. Distressed homes sitting on the market for 90 days or more often see cumulative price reductions of 10% to 20%. The longer you wait to list, the more likely you are to face a buyer's market dynamic where your negotiating position weakens over time.
The Longer You Wait, the More It Costs
Carrying costs and care expenses add up every month. If you're facing a care transition timeline, understanding your home sale options now can save thousands of dollars and significantly reduce the stress on your family. We're here to help you think through the timing without pressure.
Medicaid, Care Funding, and Home Sale Timing: The Critical Connection
For families navigating Medicaid eligibility for long-term care, the home sale isn't just a financial transaction — it's a critical piece of a larger care funding puzzle with hard deadlines and real consequences for getting the timing wrong.
Texas Medicaid (STAR+PLUS) requires individuals applying for long-term care benefits to "spend down" their assets to meet eligibility requirements. The asset limit for an individual is approximately $2,000. Home equity above that threshold typically must be liquidated — which means the home must be sold as part of the Medicaid qualification process. This isn't optional, and it isn't something that can be deferred indefinitely.
The timing pressure is significant. Families may need to complete a home sale within three to six months of a Medicaid application to meet eligibility requirements. Delays in selling — whether because of a lengthy traditional listing process or simply because the decision was postponed — can push the sale beyond the application deadline, jeopardizing Medicaid coverage and forcing families to cover care costs out of pocket during the gap period. The intersection of Medicaid planning and protecting home assets is complex enough that it warrants dedicated professional guidance.
A quick cash sale has a specific advantage in this context: it provides funds immediately to meet spend-down requirements and accelerates the Medicaid application timeline. A traditional listing, with its 60 to 120+ day timeline, may not align with the Medicaid application window — and the consequences of that misalignment can be severe. Out-of-pocket care costs at $5,000 to $7,500 per month add up fast when Medicaid coverage is delayed by a slow home sale.
This is an area where professional coordination is essential. An elder law attorney can help you understand the specific spend-down requirements for your parent's situation. A Medicaid planner can align the home sale timeline with the application process. And a trusted real estate advisor can help you choose a sale path that fits within the required window. These aren't optional consultations — they're the difference between a smooth transition and a financial crisis.
Medicaid Timelines Are Tight — And Home Sale Timing Matters
If you're navigating the intersection of a home sale and Medicaid eligibility, professional guidance can help you coordinate everything smoothly and avoid costly timing mistakes. We work alongside elder law attorneys and Medicaid planners to help families get this right.
Verifying Legitimacy: How to Spot a Trustworthy Cash Buyer in Euless
The existence of bad actors in the cash buyer space shouldn't prevent families from accessing a legitimate, helpful option. But it does mean you need to know how to tell the difference between a reputable buyer and a predatory one. The good news: the verification steps are straightforward, and legitimate buyers will pass them without hesitation.
Start with TREC licensing. If a buyer claims to be licensed, verify it at trec.texas.gov. Licensed buyers and agents are bound by professional standards and the Texas Deceptive Trade Practices Act, which gives you formal recourse against fraud or misrepresentation. Unlicensed buyers can still operate legally when purchasing for their own investment, but they operate outside direct TREC oversight.
Ask for proof of funds — documentation showing the buyer has the cash available to close. A legitimate buyer provides this without hesitation. If they stall, deflect, or offer vague assurances instead of documentation, that's a red flag.
Request a transparent offer explanation. You should understand exactly how the buyer calculated their offer — the ARV they used, the repair estimates they applied, their profit margin. If they can't or won't explain the math, you have no basis for evaluating whether the offer is fair. Our comprehensive guide to whether cash home buyers are legit in DFW walks through the full verification process in detail.
Check the company's reputation through BBB, Google reviews, and local references. Look for patterns — not just individual complaints, but recurring themes about how they treat sellers. Check TREC and Texas Attorney General databases for complaint history.
Review the purchase agreement carefully before signing. It should define all fees upfront, include an adequate option period (7–10 days is standard), allow cancellation without penalty within that period, and clearly define what "as-is" means in the context of the transaction. If the contract is vague, one-sided, or rushed, don't sign it.
Red Flags That Signal a Predatory Buyer
Be alert to these specific warning signs:
- Unsolicited offers or cold calls, especially those targeting seniors or recently bereaved families
- Requests for upfront fees or deposits — this is illegal in Texas
- Refusal to provide proof of funds or a transparent offer breakdown
- High-pressure tactics: "This offer expires today" or "You need to decide now"
- Offer changes significantly near closing — a classic bait-and-switch pattern
- No clear explanation of how the offer price was determined
- Demands to sign blank documents or contracts you haven't had time to review
- No verifiable business address, phone number, or online presence
Red Flag: Unsolicited Offers and Cold Calls
If a cash buyer contacts you out of the blue with an offer, be cautious. Predatory investors often target seniors and distressed homeowners with unsolicited offers, high-pressure tactics, and vague terms. Legitimate buyers wait for you to reach out. If you didn't initiate the contact, take extra time to verify before engaging further.
Your Legal Protections: Texas Law and Seller Rights
Whether you choose a quick cash sale or a traditional listing, Texas law provides meaningful protections for sellers — and knowing those protections gives you confidence to move forward without fear of being taken advantage of.
The Texas Deceptive Trade Practices Act (DTPA) is your primary protection against fraud and misleading actions. It applies to both licensed and unlicensed buyers, and it provides legal recourse if a buyer misrepresents the offer, the process, or the contract terms. The DTPA has real teeth — violations can result in damages, attorney's fees, and in some cases treble damages for knowing violations.
Texas law requires a Seller's Disclosure Notice for most residential sales. This document details known property conditions and must be completed honestly. Here's the critical point: even in an "as-is" sale, you are still legally required to disclose known material defects. "As-is" means the buyer accepts the property in its current condition — it does not waive your obligation to tell them about problems you know about. If you know the foundation has been repaired, the roof leaks in heavy rain, or the HVAC is failing, you must disclose it. Homes built before 1978 also require a lead-based paint disclosure. For more detail on navigating as-is sales in the DFW area, our guide on as-is home sales in DFW covers the disclosure requirements in depth.
The option period is a buyer protection that also benefits sellers by providing timeline certainty. During the option period (typically 7–10 days), the buyer has the right to inspect the property and cancel the contract without penalty. Once the option period expires without cancellation, the contract becomes more binding and your closing timeline is clearer.
Texas law also provides specific protections against elder financial abuse — statutes and avenues for seniors and their representatives to address financial exploitation. If you believe a buyer has engaged in deceptive or exploitative practices, you have recourse through TREC (for licensed individuals), the Texas Attorney General's Consumer Protection Division, and the courts. Our detailed resource on cash home buyer scams in DFW and how to vet buyers includes guidance on reporting and recourse options.
Pro Tip: Get Everything in Writing
Whether you choose a quick sale or traditional listing, insist on clear, written terms. No verbal agreements. No handshake deals. A legitimate buyer or agent will provide detailed contracts that spell out all fees, timelines, and contingencies — and they won't pressure you to sign before you've had time to review everything carefully.
What "As-Is" Really Means in Texas
"As-is" means the buyer accepts the property in its current condition, but it does NOT waive your legal obligation to disclose known material defects. You must still tell the buyer about foundation issues, roof leaks, or other problems you're aware of. "As-is" just means they're not asking you to fix them before closing — it doesn't protect you from liability for concealing known problems.
Making Your Decision: A Framework for Choosing the Right Path
By now you have a clear picture of both paths — their real costs, their real timelines, and their real trade-offs. The final step is applying that information to your specific situation. Here's a framework for thinking through it clearly.
Start with care needs. What's the timeline for your parent's transition? Is there a hard deadline — a facility deposit due, a Medicaid application window, a health situation that requires immediate placement? If the answer is days or weeks, the timeline alone may determine your path. If you have months, you have more flexibility to evaluate options carefully.
Assess financial pressure. How urgent is the need for funds? Is home equity the primary source of care funding, or do you have other resources to bridge a gap? Is there a Medicaid spend-down deadline that creates a hard timeline for the sale? These questions determine how much weight to give the speed advantage of a cash sale.
Evaluate home condition honestly. Does the home need major repairs — foundation, roof, HVAC? Or does it need primarily cosmetic updates? The answer to this question significantly shapes the traditional listing math. A home with major structural issues faces a much harder traditional listing path than one that just needs fresh paint and carpet.
Consider emotional capacity. Can you realistically handle 60 to 120 days of showings, negotiations, and uncertainty while also managing your parent's care transition? Be honest with yourself. Caregiver burnout is real, and adding a complex real estate transaction to an already overwhelming situation has a cost that doesn't show up in the net proceeds calculation. The broader context of navigating a senior living transition makes clear just how many moving pieces families are managing simultaneously.
Define success for your family. Is it maximum net proceeds, no matter the time and effort? Or is it peace of mind, speed, certainty, and the ability to focus on your parent's care? Neither answer is wrong. But being clear about what "success" means to your family is the foundation of a decision you'll feel good about.
Questions to Ask Yourself Before Deciding
Decision Checklist: Before You Choose a Path
- When does my parent need to move? Is there a hard deadline?
- How much do I need to fund care, and is home equity the primary source?
- What repairs does the home need, and how much would they cost?
- Can I emotionally and logistically handle a 60–120 day listing process?
- Are there multiple heirs who need to agree on the approach?
- Is there a Medicaid application deadline that creates a sale timeline?
- Do I have an elder law attorney, Medicaid planner, or trusted advisor?
- What does "success" mean for my family in this situation?
Get professional guidance before finalizing your decision. An elder law attorney can clarify Medicaid implications. A Medicaid planner can align the sale timeline with the application process. A trusted real estate advisor — one who understands both the traditional and cash sale paths — can help you evaluate your specific home's position in the Euless market. For a detailed comparison of how different sale approaches play out for senior homeowners in this area, our analysis of senior home sale options in DFW provides additional perspective.
And trust your gut. The "right" choice is the one that aligns with your family's actual values and needs — not what you think you "should" do, not what a sibling thinks sounds better, and not what maximizes a number on paper if it comes at the cost of your family's wellbeing during an already difficult time.
Frequently Asked Questions
How much less money will I get if I sell my Euless house fast for cash compared to selling it traditionally?
You can expect a quick cash sale to offer roughly 70–85% of your home's post-renovation value — which typically translates to 15–30% less than the potential top-dollar price of a traditional listing. However, that lower offer price is offset by avoiding significant selling costs: agent commissions (5–6%), inspection repair credits (5–15%), carrying costs of $800–$1,500 per month, staging, and cleanout. When you run the actual net proceeds numbers, the gap between a cash sale and a traditional listing often shrinks substantially — and in some cases, especially for heavily distressed homes with long listing timelines, the cash sale actually yields comparable or higher net proceeds after all costs are accounted for.
Is it better to sell my parents' inherited house in Euless quickly or list it for market value, especially if it needs repairs?
If immediate funds are needed for care, or the house requires extensive repairs — foundation, roof, HVAC — a quick sale is often the better path. It provides certainty, speed, and eliminates the stress and cost of repairs, extended carrying costs, and a lengthy listing process. If time is not a factor and the house needs only minor cosmetic work, listing traditionally may yield more net profit — but with significantly added complexity, emotional burden, and financial risk from inspection credits and price reductions. For inherited properties with multiple heirs, a quick sale also eliminates the family conflict that often accompanies listing decisions, providing a clean and fast resolution.
What protection do I have if a cash buyer tries to pressure me or change the offer price last minute in Texas?
You have strong protections under the Texas Deceptive Trade Practices Act (DTPA), which applies to both licensed and unlicensed buyers and provides legal recourse against fraud, misrepresentation, and deceptive practices. Ensure your purchase agreement includes a clear option period (7–10 days) that allows you to cancel without penalty, defines all fees upfront, and requires the buyer to provide proof of funds. Legitimate buyers will not use high-pressure tactics or change terms arbitrarily — if they do, you have recourse through TREC (for licensed buyers), the Texas Attorney General's Consumer Protection Division, and the courts. If an offer changes significantly near closing, you are not obligated to proceed.
How does selling my parent's home for cash affect their Medicaid application in Texas?
Selling the home liquidates an asset that typically must be "spent down" to meet Texas Medicaid (STAR+PLUS) eligibility for long-term care, which requires assets below approximately $2,000. A quick cash sale provides funds immediately to meet these spend-down requirements, which can actually accelerate Medicaid eligibility compared to a traditional listing that takes 60–120+ days. The critical factor is coordinating the home sale timeline with the Medicaid application process — delays in selling can push the sale beyond the application window, jeopardizing coverage and forcing out-of-pocket care payments at $5,000–$7,500 per month or more. Working with an elder law attorney and Medicaid planner before initiating the sale is strongly recommended.
How do I verify a "cash buyer" is legitimate and not a scammer targeting seniors in Euless?
Start by checking TREC licensing at trec.texas.gov if the buyer claims to be licensed. Request proof of funds — documentation showing they have the cash available to close — and ask for a clear, step-by-step explanation of how they calculated their offer (ARV, repair deductions, profit margin). Research the company's reputation through BBB, Google reviews, and local references, and check TREC and Texas Attorney General databases for complaint history. A legitimate buyer will pass all of these checks without hesitation, allow you adequate time to review offers, and never use high-pressure tactics or request upfront fees. If any of these steps produce red flags, trust your instincts and walk away.
What are the actual costs involved if I try to fix up my inherited house in Euless and list it myself?
For a distressed Euless home, repair costs alone can run $10,000 to $50,000 or more — foundation repair ($5,000–$25,000+), roof replacement ($8,000–$15,000+), HVAC replacement ($5,000–$8,000+) — before you've addressed any cosmetic updates. Add staging ($2,000–$5,000), professional cleaning ($500–$1,000), landscaping and curb appeal ($300–$1,000), permits, increased utility bills during the listing period, property taxes, homeowner's insurance, and potentially storage fees for the contents. You also forgo the expert pricing, market knowledge, and negotiation support that a real estate agent provides. For many distressed homes, these costs exceed the difference between a cash sale and a traditional listing price — making the repair-and-list path financially counterproductive.
Ready to Understand Your Options? Let's Talk Through This Together
We started Sage Senior Support because of our own family's journey — navigating Alzheimer's, caregiving, and the overwhelming question of what to do with a parent's home when everything else is already too much. We know what it feels like to stand in that house, looking at the harvest gold carpet and the foundation crack, and wonder if you're making the right call.
What we've learned — through our own experience and through walking alongside hundreds of families since — is that there's no universally right answer. There's only the answer that fits your family's actual situation, values, and needs. Our job isn't to push you toward any particular path. It's to help you see all your options clearly, understand the real numbers, and make a decision you'll feel confident about — whether that's a quick sale, a traditional listing, or something in between.
Whether you're leaning toward a quick sale, exploring traditional listing, or still undecided, we're here to help you think through what makes sense for your family's specific situation. No pressure, no sales pitch — just honest guidance from people who've been through this themselves.
You Don't Have to Figure This Out Alone
The home sale is one piece of a much larger transition — and it deserves to be handled with the same care and clarity as every other part of your parent's journey. If you're ready to have a real conversation about your options, we're ready to listen.
Start with a free, no-obligation consultation. We'll talk through your parent's care situation first, then help you understand what the home sale path looks like from both directions — so you can make the choice that honors your family's needs and your parent's legacy.